
The market produced turbulent but ultimately above-average gains through the first half of the year. At 2026’s midway point, the S&P 500 had delivered a total return (price plus dividends) of 10%, which is right in line with the long-term mean for the index’s full-year annual returns—from here, anything on top of that is gravy.
Naturally, the index’s best stocks had performed much, much better. Dell Technologies (DELL) popped by 245%. One of our best growth stock picks, Micron (MU), was up more than 300%. And SanDisk had beaten every last component with wild gain of almost 860%.
Good for them, but not every stock joined in on the fun. In fact, almost a third of the S&P 500 sat in the red through July 1. However, some of those names could be poised for a renaissance before the year is through.
Today, I’m going to look at 10 of the best stocks to buy for a rebound across the rest of 2026. While these companies didn’t give Wall Street much to cheer about through 2026’s first half, equity researchers believe the remaining few months (and beyond) could deliver much more to celebrate.
Editor’s Note: Tabular information presented in this article is up-to-date as of Sept. 15, 2026.
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
The Best Rebound Stocks to Buy Now
How did I pick the best stocks for a resurgence in 2026’s back half?
I started with stocks that had declined by 10% or more through the first six months of 2026. That represents at least 20 percentage points of underperformance against the S&P 500. But I didn’t limit the list to just the large-cap index—I broadened the scope to the S&P Composite 1500, which includes small-, mid-, and large-cap stocks.
From there, I looked for stocks that analysts surveyed by S&P Global Market Intelligence believe have at least 20% upside from their midyear price, as determined by their consensus 12-month price targets.
Lastly, I ranked these stocks based on their consensus analyst ratings from S&P Global Market Intelligence. The consensus rating is the average of all known analyst ratings of the stock, boiled down to a numerical system where …
1-1.5 = Strong Buy
1.5-2.5 = Buy
2.5-3.5 = Hold
3.5-4.5 = Sell
4.5-5 = Strong Sell
In short: The lower the number, the better the overall consensus view on the stock. All stocks here are rated at least 1.5 or below, meaning they’re all considered Strong Buys right now.
Let’s take a look at the best stocks to buy for a rebound bid for the rest of the year. All stocks are listed in reverse order of the consensus rating (from worst to best). I’ll tell you about the company, outline its analyst ratings and projected upside, and provide some of the bull case from one of each company’s covering analysts.
#10 Best Rebound Stock to Buy: AppFolio
- Sector: Information technology
- Market capitalization: $7.8 billion
- 2026 first-half return: -31%
- Consensus analyst rating: 1.44 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 44%
About AppFolio (APPF): AppFolio provides software-as-a-service applications and services to the real estate industry. For instance, its Property Manager Core provides real estate accounting functions for small property management companies; its Property Manager Plus services larger housing portfolios with advanced analytics, affordable-housing tools, and premium integrations; and its Property Manager Max provides leasing CRM, dedicated customer success management, and more for very large property operators.
Analyst Ratings: 8 Buys, 1 Hold, 0 Sells
Why the Analysts Still Believe: “We view APPF as a high-quality vertical software and services company in the U.S. property management software market with a strong track record of innovation. This has allowed the company to carve out deep moats in the SMB and mid-market categories of its TAM. We believe APPF continues to have a strong growth runway from here, particularly in its ability to extract more pricing via additional solutions for both property managers and residents. … [Second-quarter] commentary around new product uptake (resident services, agentic AI performers) remained upbeat, which is supportive of our positive thesis tied to dismissal of the AI disrupter narrative and the meaningful revenue opportunity associated with these two product cycles.” — Keefe, Bruyette & Woods analysts Ryan Tomasello and Jade Rahmani (Outperform)
Related: 14 Best Investing Research & Stock Analysis Websites [2026]
#9 Best Rebound Stock to Buy: Trimble
- Sector: Information technology
- Market capitalization: $13.7 billion
- 2026 first-half return: -35%
- Consensus analyst rating: 1.38 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 57%
About Trimble (TRMB): Trimble is a technology provider whose hardware, software, and services help connect the physical and digital worlds. Its offerings are heavily geared toward the construction industry, including 3D software for architecture, business management tools, digital fabrication solutions, project management software for contractors, and more. But its offerings are also used in utilities, forestry, and agriculture. It also has a transportation unit that includes maps and transportation management products, but Axios recently reported that Trimble is looking to sell that arm of the business.
Analyst Ratings: 12 Buys, 1 Hold, 0 Sells
Why the Analysts Still Believe: “We believe Trimble is doing well executing against its strategic plan to deliver both growth and profitability. In our view, the unsolicited interest in the company’s T&L business suggests that the potential value of the business is higher than investors may be crediting the company for, particularly in an improving macro environment. We have seen little evidence of AI disrupting or impacting Trimble and continue to believe Trimble will bring AI capabilities to its customers. We believe the need for both a deterministic workflow and the capabilities offered by AI models is compelling from a cost-savings standpoint, with Trimble likely to benefit from broader adoption.” — Oppenheimer analysts (Outperform)
Make sure you sign up for The Weekend Tea, our free weekly newsletter that over 10k monthly readers use to level up their money know-how.
#8 Best Rebound Stock to Buy: Microsoft
- Sector: Information technology
- Market capitalization: $3.7 trillion
- 2026 first-half return: -23%
- Consensus analyst rating: 1.36 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 54%
About Microsoft (MSFT): Microsoft is one of the most dominant names in technology and among the largest tech stocks on the planet. The average person knows Microsoft for its iconic Windows and Office productivity software for personal computers, as well as its Xbox gaming console and related software. But Microsoft also is a major player in cloud computing, via its still-growing Azure cloud services, and an emerging titan in artificial intelligence—a position it further cemented in 2025 with the announcement of a strategic partnership with Anthropic (as well as a chipmaker I’ll get to next). It’s also an aggressive dividend grower.
Analyst Ratings: 52 Buys, 3 Holds, 0 Sells
Why the Analysts Still Believe: “Microsoft continues to pursue long-term growth through its artificial intelligence (AI) and cloud investments. CEO Satya Nadella sees GenAI as a rare change to a fundamental computing paradigm, and Microsoft is moving aggressively to exploit the opportunities opened by GenAI, as demand currently outstrips the supply of its cloud services. Although not immune to macroeconomic challenges (such as declines in the PC original equipment manufacturers (OEM) market and in digital advertising), Microsoft has about as diversified and strong a set of assets as any company in the technology arena—and may even be seen as a safe haven for investors in uncertain times. The company is one of a few names with a complete, integrated commercial product set aimed at enterprise efficiency, cloud transformation, collaboration, and business intelligence. It also has a large and loyal customer base, a substantial cash cushion, and a rock-solid balance sheet. Market concerns over GenAI investments have dogged MSFT shares over the last year, though these concerns are belied by the company’s strong revenue and margin performance.” — Argus Research analyst Joseph Bonner (Buy)
Related: 7 Best Value Stocks to Buy for the Rest of 2026
#7 Best Rebound Stock to Buy: Rithm Capital
- Sector: Financials
- Market capitalization: $5.5 billion
- 2026 first-half return: -12%
- Consensus analyst rating: 1.36 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 44%
About Rithm Capital (RITM): Rithm Capital is a specific type of real estate investment trust (REIT) that deals not in physical real estate, but mortgages. Most mortgage REITs (mREITs) will own residential and/or commercial mortgages, mortgage-backed securities (MBSes), and other real estate “paper.” They borrow money at short-term interest rates to buy the mortgage-related securities, then earn income from the interest generated by these products. They also tend to be extremely high-yield dividend stocks; RITM pays almost 11% right now. Rithm Capital itself is more of a “hybrid” mREIT that owns numerous businesses, including alternative asset management. It invests in residential mortgages loans, consumer loans, single-family rentals, mortgage servicing rights (MSRs), residential transitional loans, secured lending and structured products, and commercial real estate.
Analyst Ratings: 11 Buys, 0 Holds, 0 Sells
Why the Analysts Still Believe: “We believe RITM remains a best-in-class REIT that has diversified its revenue streams and has consistently delivered strong earnings comfortably above its dividend. Book value has remained stable, and the company has generated high-teens operating ROEs (although economic returns have been lower). … We think the company provides an attractive combination of strong current returns and upside optionality for its valuation to re-rate up as it continues to grow as an alternative asset manager..” —Keefe, Bruyette & Woods analysts (Outperform)
Related: 10 Monthly Dividend Stocks for Frequent, Regular Income
Need Help Picking Stocks? Consider These Top-Rated Services
#6 Best Rebound Stock to Buy: CRH plc
- Sector: Materials
- Market capitalization: $59.0 billion
- 2026 first-half return: -14%
- Consensus analyst rating: 1.30 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 28%
About CRH plc (CRH): The Dublin-based company is a leading global provider of building materials and construction solutions. It manufactures aggregates (crushed stone, sand, and gravel), cement, asphalt, ready-mixed concrete, and more. These materials are used for transportation networks, critical utilities, and commercial and residential building projects.
Analyst Ratings: 23 Buys, 1 Hold, 0 Sells
Why the Analysts Still Believe: “The diversity of business will clearly help CRH in what is going to be a turbulent year of inflation particularly in Europe, solid demand in North America materials, and rising prices in many products. The company’s recent M&A also helps cushion the inflation impact. The recent deals do show somewhat of a shift more towards water infrastructure (buying Axius) and away from outdoor living (sale of decking/mulch) in a trend that we believe will continue. We remain Buy-rated and note the shares have underperformed US-based material peers. We believe a catch up to these names is underway.” — Truist Managing Director Keith Hughes (Buy)
Related: 9 Apps With Free Stocks for Signing Up [Get Free Shares]
#5 Best Rebound Stock to Buy: Waystar Holding
- Sector: Healthcare
- Market capitalization: $5.2 billion
- 2026 first-half return: -37%
- Consensus analyst rating: 1.29 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 62%
About Waystar Holding (WAY): Waystar Holding provides a cloud-based software solution for healthcare payments. Its platform offers financial clearance, patient financial care, claim and payer payment management, denials prevention and recovery, clinical integrity and revenue capture, and analytics and reporting solutions. These solutions serve a variety of healthcare providers, including hospitals, healthcare systems, hospice care, internal medicine, radiology, laboratories, ambulance operators, and more.
Analyst Ratings: 23 Buys, 1 Hold, 0 Sells
Why the Analysts Still Believe: “We remain buyers of the stock and continue to view WAY as a core long-term [healthcare IT] holding. In our view, the company remains positioned to capitalize on the AI-enabled transformation of revenue cycle management via stronger pricing, an expanding [total addressable market], and increased value-add for clients. We also believe that Waystar remains a category leader in end-to-end RCM software (which clients desire over point solutions), leveraging its competitive position and scale advantages to enhance the platform with innovations that drive client value. Moreover, we believe innovation momentum is driving an uptick in pipeline activity, size, and bookings performance, highlighted by a continuation of strong win rates and an uptick in larger deal sizes.” — William Blair analysts Ryan Daniels and Jared Haase (Outperform)
Related: 8 Best Wealth + Net Worth Tracker Apps [View All Your Assets]
#4 Best Rebound Stock to Buy: Churchill Downs
- Sector: Consumer discretionary
- Market capitalization: $5.7 billion
- 2026 first-half return: -21%
- Consensus analyst rating: 1.25 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 46%
About Churchill Downs (CHDN): Churchill Downs operates live and historical racing entertainment venues, online gambling businesses, and regional casino gaming properties in the United States. Its racing operations include live and historical parimutuel (all bets are combined in a pool) racing-related activities at Churchill Downs Racetrack, as well as historical racing properties in Kentucky, Virginia, and New Hampshire. It also provides racing event-related services, including admissions, personal seat licenses, sponsorships, television rights, and other miscellaneous services, as well as food and beverages services. Its businesses also include casino and racetrack operations, as well as horse racing wagering for TwinSpires.com, BetAmerica.com, and other white-label platforms.
Analyst Ratings: 12 Buys, 0 Holds, 0 Sells
Why the Analysts Still Believe: “We argue CHDN is one of the best growth stories across gaming, reflecting a unique pipeline of high [return on investment] expansion projects, synergy opportunity with the P2E and Exacta acquisitions, and organic growth drivers for the still-nascent [historical horse racing, an electronic gambling machine] category. We argue concerns around Kentucky Derby pricing power and related multiple contraction are overdone, with an attractive setup into [the 152nd Kentucky Derby] potentially helping improve sentiment. While horse racing viewership continues to face secular headwinds, we see potential for high-growth [online sports betting] operators to grow the total addressable market while CHDN continues to develop a unique flywheel and moat as the market leader in live, historical, and online horse racing. Valuation sits near the high end of peer group, though warranted, in our view, given CHDN’s unique growth drivers and portfolio of assets.” — Stifel analysts (Buy)
Related: How to Choose a Financial Advisor
#3 Best Rebound Stock to Buy: Boot Barn Holdings
- Sector: Consumer discretionary
- Market capitalization: $4.1 billion
- 2026 first-half return: -10%
- Consensus analyst rating: 1.25 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 35%
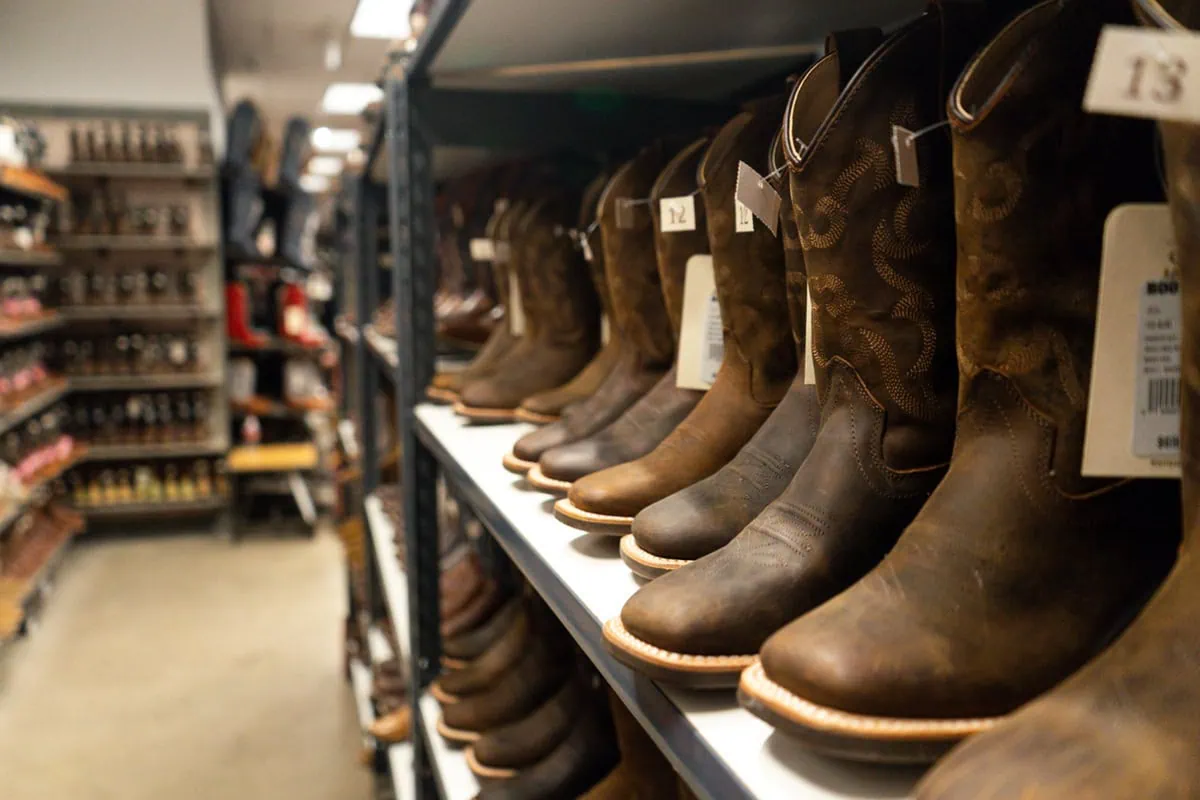
About Boot Barn Holdings (BOOT): Boot Barn operates more than 500 of its specialty retail stores. It’s a “lifestyle” chain that sells Western and work-related footwear, apparel, and accessories, such as shirts, cowboy hats, belts (and belt buckles!), rugged footwear, overalls, safety-toe boots, flame-resistant and high-visibility clothing, gifts, and home merchandise. Just some of its brands include Levi’s, Laredo, Wrangler, Carhartt, Stetson, Timberland Pro, Wolverine, and Durango.
Analyst Ratings: 15 Buys, 1 Hold, 0 Sells
Why the Analysts Still Believe: “Boot Barn is the dominant retailer in two niche and underserved categories—westernwear and workwear. We believe BOOT is an underappreciated growth story and see potential for BOOT to add 400 stores over the next five years, and this should drive a ~13.5% [earnings per share compound average growth rate through fiscal year 2030]. Plus, we believe BOOT will navigate ongoing tariff environment uncertainty and cost inflation pressures from elevated oil prices better than many of its “mom & pop” rivals will, which could accelerate share gains for BOOT and its exclusive brands, in our view. … [After a recent meeting with management, UBS says] the main comp drivers appear to be transactions, AUR, digital growth, and category strength in work boots and denim. Management said that historically comps have tended to be transaction driven, while AUR usually contributes around 1.5–2% annually, with this year expected closer to 2–3%.” — UBS analyst Jay Sole (Buy)
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
#2 Best Rebound Stock to Buy: Somnigroup International
- Sector: Materials
- Market capitalization: $14.0 billion
- 2026 first-half return: -12%
- Consensus analyst rating: 1.20 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 20%
About Somnigroup International (SGI): Somnigroup is one of the largest bedding companies in the world, designing, manufacturing, distributing, and retailing bedding products in the U.S. and internationally. It operates a portfolio of brands including Mattress Firm, Dreams, Tempur-Pedic, and SOVA, and it licenses other brands such as Sealy, Tempur, and Stearns & Foster.
Analyst Ratings: 10 Buys, 0 Holds, 0 Sells
Why the Analysts Still Believe: Rival Sleep Number recently filed for Chapter 11 bankruptcy protection. “This could mean a sizeable market share opportunity up for grabs. Recall, the company ended 1Q’26 with 577 stores and TTM sales of $1.4 billion. We think SGI could capture market share; there’s significant market share opportunity. There’s a high degree of competitive overlap. Within a 5-mile radius, ~95% of SNBR locations have a Mattress Firm store nearby; ~16% have a Tempur-Pedic store nearby. Over ~96% of SNBR locations have at least one Mattress Firm store within a 15-mile radius. … Big picture, SGI’s increasingly strong competitive position is shining through.” — UBS analyst Dan Silverstein (Buy)
Related: How Long Will My Savings Last in Retirement? 4 Withdrawal Strategies
#1 Best Rebound Stock to Buy: Wynn Resorts
- Sector: Consumer discretionary
- Market capitalization: $9.0 billion
- 2026 first-half return: -19%
- Consensus analyst rating: 1.19 (Strong Buy)
- Consensus 12-month price upside from 6/30/26 close: 36%
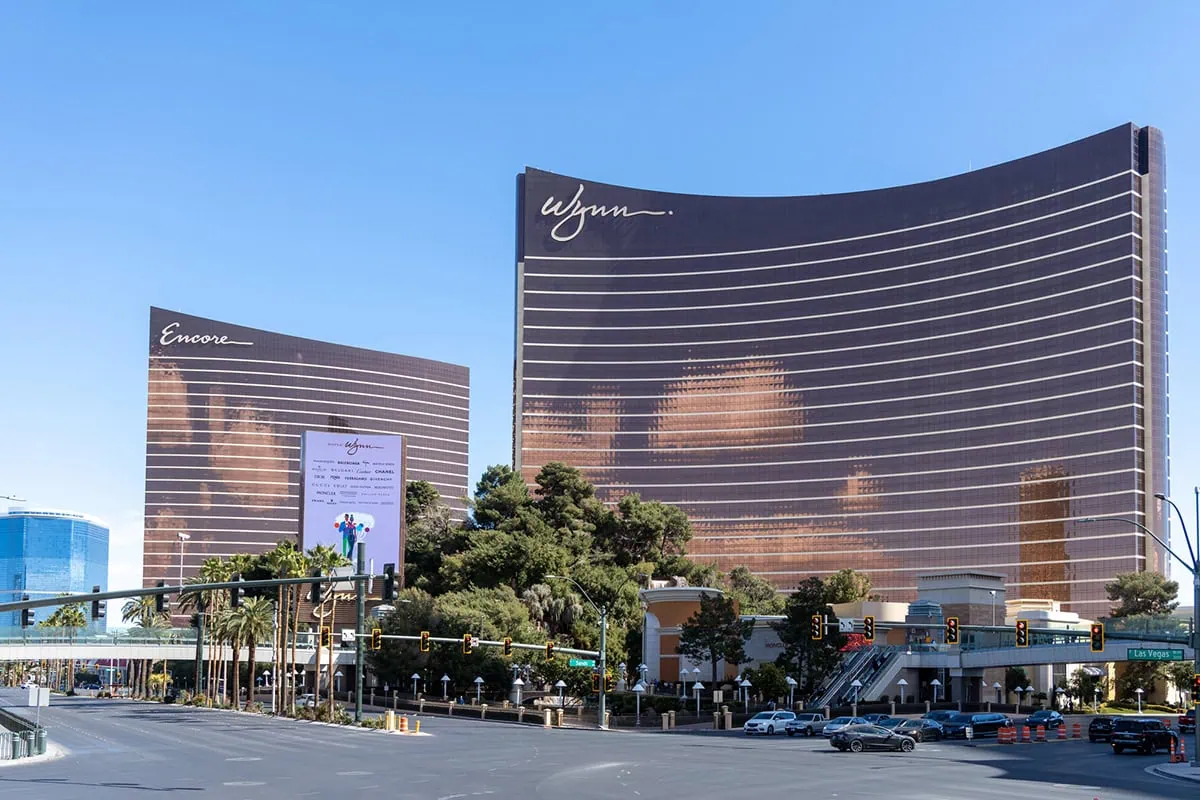
About Wynn Resorts (WYNN): Wynn Resorts is one of the world’s top casino and resort owners. It owns and operates Wynn Las Vegas, Wynn Macau, Wynn Palace, Cotai, and Wynn Mayfair, and operates Encore Boston Harbor. It’s also building an integrated resort in Ras Al Khaimah, United Arab Emirates (UAE), which is set to open in 2027. Its properties include casino spaces, private gaming salons, rooms, health clubs, spas, salons, pools, restaurants, retail space, meeting and convention space, entertainment centers, beach clubs, and more.
Analyst Ratings: 21 Buys, 0 Holds, 0 Sells
Why the Analysts Still Believe: “WYNN is well positioned with properties skewed towards more affluent and resilient customers at resort properties in desirable locations. Vegas thrives at the highest end of the market, making recent market softness less of an issue (though we’re seeing signs of market inflection). Macau continues its recovery to pre-COVID/junket ban levels with WYNN well positioned at the important premium mass level and a new hotel tower planned to boost capacity. But we see the biggest upside in UAE as regional volatility quiets down, and estimate up to $50/share in incremental value to the stock based on a management fee and 40% ownership. With leverage declining and [free cash flow] inflecting (post-UAE opening), we think WYNN is poised for more capital returns to shareholders.” — Truist Managing Director Barry Jonas (Buy)
Related: How Can I Lower My Taxes in Retirement? 8 Proven Strategies
What If I Need Help Picking Stocks?
Motley Fool Stock Advisor is a stock picking service that espouses my favorite, plain-vanilla trading style: buy-and-hold. Fool analysts provide recommendations for both “Steady Eddies” and potential high-flying stocks with sound fundamentals—exactly the combination of holdings you want to generate strong performance without risking extremely high volatility.
Importantly, Stock Advisor doesn’t just give you a list of tickers and call it a day. It also provides investment rationales and research for each pick to help educate you before you buy.
Stock Advisor has returned more than 900% since its founding in February 2002, more than tripling the S&P 500 over that time (as of 6/11/26). You can join this service at a discounted rate for the first year, and get a 30-day membership-fee-back period, if you sign up for Stock Advisor today.
- Motley Fool Stock Advisor is a stock service that provides recommendations for both "steady Eddie" and high-flying stocks, as well as a few ETFs for investors who want diversified holdings, too.
- Just getting started? Stock Advisor provides 10 "Foundational Stocks" you can use to anchor your portfolio.
- You're not alone! Stock Advisor membership also gives you access to a community of investors who also want to outperform the market and love talking shop.
- Enjoy access to GamePlan: Motley Fool's financial planning hub, which includes advice on personal finances, taxes, retirement, and more, as well as calculators and other financial tools.
- Limited-Time Offer: Get your first year with Stock Advisor for $99 (vs. $199 usual value)—a 50% discount for new members!—by clicking our link.*
- Discounted introductory price
- Strong outperformance compared to the S&P 500
- High overall average return for stock picks
- High renewal price
- Not every stock is a winner
Read More on WealthUpdate
- Presidential Stock Market Performance: The Best (And Worst) Commanders-in-Chief
- Acorns Early vs. Chase First Banking [Which Is the Better Debit Card?]
- Dividend Kings: The Full List of American Dividend Royalty
Please Heart ❤️, Follow and Subscribe
Did you find this article helpful?
1. Click the Heart Button.
2. Follow WealthUpdate —-> https://flipboard.com/@WealthUpdate
3. Subscribe to Retire With Riley, our free weekly retirement planning newsletter.