
What do the market’s best dividend stocks look like?
Annoying an answer as this is, it depends on what you’re looking for. Maybe you want prolific dividend growth, for instance. Or maybe you’re looking for high current yield.
But today, I want to focus on so-called “total package” dividend stocks: top-quality companies that pay well-covered dividends that amount to above-average yields. In some cases, these companies have been growing their distributions, and a few deliver truly high yields. However, the main point across the board here is these companies’ overall quality.
Read on as I highlight Wall Street’s best dividend stocks, as rated by research firms that routinely cover these companies. I’ll also take some time to explain the importance of dividend income and sustainable payouts.
Editor’s Note: Tabular data presented in this article is up-to-date as of Nov. 9, 2026.
Featured Financial Products
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
Table of Contents
Why Dividend Stocks?
Dividend stocks can do wonders for the long-term performance of your portfolio. These companies pay a regular flow of their profits directly back to shareholders, meaning you receive some sort of return—even when share prices aren’t cooperating.
Stocks that can both grow and pay dividends are the ultimate long-term stocks given just how much in additional returns they can generate over the long term.
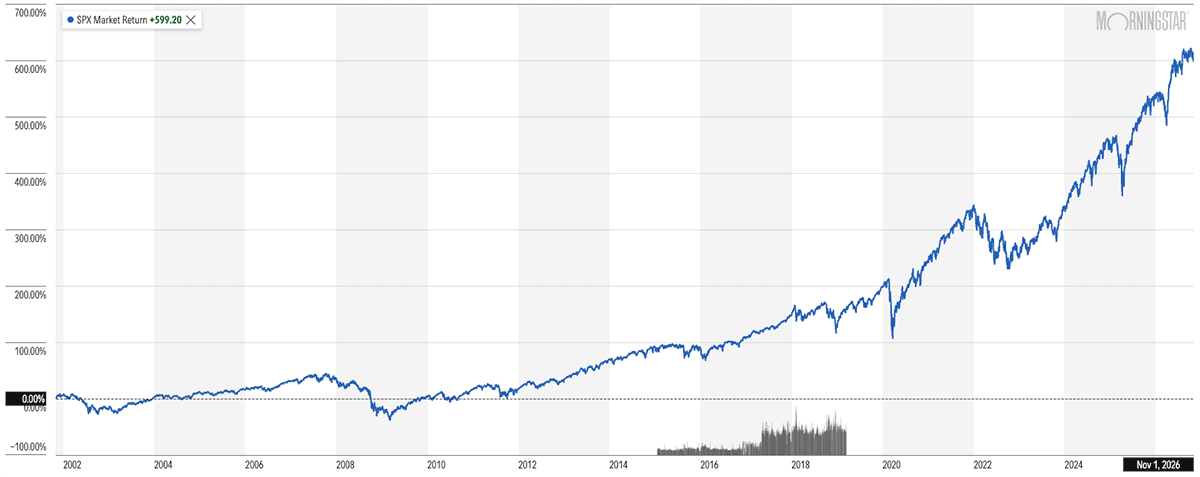
Here’s a look at the return someone could expect if they received just the price returns from the S&P 500 over the past 25 years:
Now look at how much better the return is when you factor in dividends had you had reinvested those dividends back into the S&P 500 (returns illustrated by an S&P 500-tracking ETF; note that expenses are included in performance):
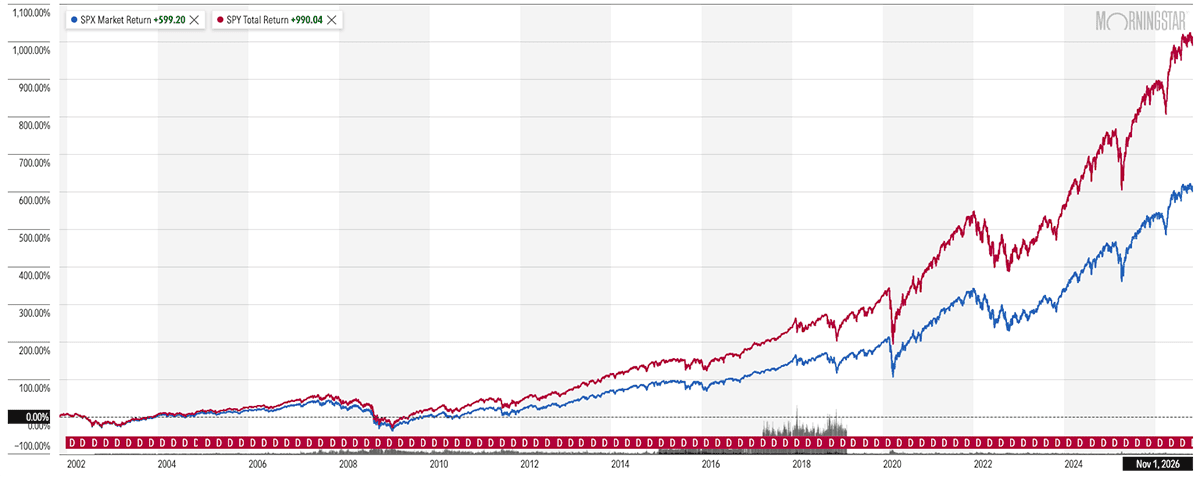
The price return is right around 600%. The total return (price plus dividends) is about 990%!
Just like price return on stocks can be improved upon with dividends, though, a stock that pays dividends but doesn’t go anywhere isn’t exactly ideal, either. Thus, the best dividend stocks will provide both a steady baseline of income and provide you with the potential for meaningful price upside.
Dividend Yields (And Dividend Safety)
Dividend yield is a simple calculation—annual dividend / price x 100—that can mean a world of difference for investors, especially those reliant on income.
But dividend yield isn’t everything. Sometimes, stocks with high yields can look more attractive, but they’re actually flashing a warning signal that the dividend isn’t sustainable. You see, a company can get a very high annual dividend yield in two very different ways: the dividend growing very rapidly, or the share price falling very quickly.
For example, Alpha Corp., which trades for $100 per share, pays a 75¢-per-share quarterly dividend, or $3 across the whole year. It yields 3.0%. In a month, however, it yields 6.0%. Here are two ways that could have happened:
- Alpha Corp. doubled its dividend to $1.50 per share quarterly, good for a $6-per-share annual dividend. The share price stays the same. ($6 / $100 x 100 = 6.0%)
- Alpha Corp. kept its dividend at 75¢ quarterly ($3 annually), but its share price plunged in half to $50 per share. ($3 / $50 x 100 = 6.0%)
In one of those scenarios, Alpha Corp. has a very safe dividend. In the other one, Alpha’s dividend could be ready to implode.
So, if you’re sniffing out the best dividend stocks to buy for 2026, make sure you’re not just looking at yield, but also gauging a dividend’s safety. Among other things, you’ll want to look at payout ratio, which determines what percentage of a company’s profits, distributable cash flow, and other financial metrics (depending on the type of stock) are being used to finance the dividend. Generally speaking, the lower the payout ratio, the more sustainable the payout.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
Earn a Dividend Match With Plynk**
- Plynk® is a dividend-friendly app that offers commission-free trades* on 5,000 stocks and more than 3,400 ETFs, and also supports mutual funds and cryptocurrencies.
- Plynk offers a cash match of 25% on dividend income that allows you to earn up to $250 extra each year.**
- Track your dividends and interest with Income Hub.
- Earn a 3.55% APY on uninvested cash.
- Plynk charges no account opening fees, and you can start investing for as little as $1.
- No account fees
- Smart design and smooth user experience
- Fractional shares
- Designed for beginning investors
- Virtual portfolios and simulated trading
- 25% dividend match
- Earn interest on uninvested cash
- One of the best automated investing programs we've seen (Steady Start)
- Elite educational resources and tools
- Lacks features such as options trading and advanced charting that more experienced traders prefer
How I Chose the Best Dividend Stocks to Buy
Before I started this article, I was video calling a colleague and joked, in a pseudo-philosophical voice, “What is a good dividend stock, anyways?”
But I was only partly kidding. What’s ideal to one investor might not fit the bill for another. Ultimately, though, I coalesced around safe dividends, with some capacity to grow, sporting above-average yields, paid by larger (and thus likelier to be more stable) companies. Specifically, they have to …
- Be in the S&P 500.
- Have a yield greater than 1.5%, to ensure they’re better than the overall market. Most of the stocks on this list yield more than 2%. (If that’s too low a baseline yield for you, I suggest you instead read our list of high-yield dividend stocks, where 5%-plus yields are the norm.)
- Have an earnings payout ratio below 70%. This is a generally safe level where there’s still at least some room for dividend growth, and the lower the payout ratio, typically the more growth potential there is. (Note: Free cash flow payout ratio is an even better metric, but screening data for this tends to be unreliable.)
- Have at least a consensus Buy rating according to analysts tracked by S&P Global Market Intelligence. S&P boils down consensus ratings down to a numerical system where anything less than 1.5 is a Strong Buy, 1.5 to 2.5 is a Buy, between 2.5 and 3.5 is a Hold, 3.5 to 4.5 is a Sell, and anything greater than 4.5 is a Strong Sell. In this case, I only included stocks with a 2.0 rating or less—so at least a pretty firm consensus Buy rating, if not an outright Strong Buy.
I also limited the energy sector to just two stocks. Energy companies were extremely overrepresented in the screen; most problematic is that several sport variable dividends that rise and fall based on available cash flow, which is largely tethered to the motion of energy prices. So a 3% yield today could be 1% in a year, 2% the year after, and so on. The rest of the list is populated with stocks that have more traditional dividend programs—regular payouts that typically only change when the company announces a hike.
The equities here are listed in reverse order of their consensus analyst rating, starting with the worst-rated stock and ending with the best-rated stock.
Related: 15 Dividend Kings for Royally Resilient Income
10. Bunge Global
- Sector: Consumer staples
- Market cap: $18.9 billion
- Dividend yield: 3.0%
- Consensus analyst rating: 1.56 (Buy)
Bunge Global (BG) is a leading agribusiness and food company, operating across the entire agricultural supply chain through its many subsidiaries. All told, its operations span roughly 23,000 employees across more than 300 facilities in over 40 countries.
The U.S.-headquartered but Switzerland-incorporated firm is a leading global oilseed processor and producer of vegetable oils and protein meals. It sources, processes, and distributes grains such as soybeans, wheat, and corn. It produces agricultural products such as fertilizers and sugars. And that’s just some of what this ag giant does.
Related: 10 Best Alternative Investments [Options to Consider]
Bunge has been a “patience stock” for years thanks to lower margins on crush (the process that produces soybean oil and protein meal), as well as delays to its proposed mega-acquisition of Canadian grain handling business Viterra. Investors finally started to see their patience pay off in early 2026; shares have backslid over the past few months, erasing much of those gains, but Wall Street’s pros remain optimistic on the stock.
“We are surprised by yesterday’s negative reaction to the results/outlook, particularly given the setup for 2027, which should allow BG to build on the ~$11 2H26 EPS run rate given incremental Viterra synergies, initial returns on capital projects, significant share buybacks, improving merchandising environment, and potential recovery in Brazil crush margins,” BMO Capital Markets Analyst Andrew Strelzik, who rates the stock at Outperform (equivalent of Buy), wrote after the company’s second-quarter earnings report in late October.
Strelzik is one of eight analysts with a Buy-equivalent rating on Bunge. That compares well against just one Hold and no Sells.
BG, meanwhile, can pay investors at least a modest sum for their patience. The 3% yield, on a quarterly dividend of 72¢ per share, is more than a percentage point better than what you’ll get from the S&P 500. That dividend has also grown by a decent 37% over the past five years, and it’s as safe as you could want it, with Bunge maintaining a conservative payout ratio of 25% of 2027 profit estimates.
Featured Financial Products
Related: The 7 Best REITs to Buy for the Rest of 2026
9. Avery Dennison
- Sector: Consumer discretionary
- Market cap: $14.4 billion
- Dividend yield: 2.1%
- Consensus analyst rating: 1.55 (Buy)
Avery Dennison (AVY) is a materials science and digital identification solutions provider—an odd bird, but one with a ton of practical applications.
For instance, it offers pressure-sensitive label materials, performance tapes, and other adhesive-based materials. It provides graphics and reflective products for commercial sign companies, digital printers, and architectural firms. It makes reflective films that are used in traffic and safety, pressure-sensitive vinyl and specialty materials for digital imaging. But it’s also a leader in radio-frequency identification (RFID), which companies like Walmart (WMT) can use in inventory management and supply chain visibility.
Related: 8 Best High-Yield Dividend ETFs for Income-Hungry Investors
Avery Dennison technically belongs to the consumer discretionary sector, but it has elements of materials and industrials. All of that still makes it a cyclical business whose top and bottom lines can ebb and flow from one year to the next. Regardless, it has built up a 16-year streak of consecutive dividend increases, making it not just one of the best dividend stocks to buy now, but one of the top dividend-growth stocks, too.
The most recent improvement, announced in late April 2026, was a 6% hike to an even $1 per share. The distribution represents only 35% of its expected earnings for 2027, which provides some flexibility.
The announcement came just a couple days after it reported a strong Q1, which it followed up with better-than-expected Q2 and Q3 results in July and October, respectively.
“AVY posted a solid 3Q beat as the expected Mats customer de-stock was not as extreme as feared (with some being pushed to 4Q),” says John P. McNulty, U.S. Chemicals Analyst at BMO Capital Markets, who rates the stock at Outperform (equivalent of Buy). “We see the results/outlook as solid in a tough environment (high raws, muted consumer), but the upcoming inflection in IL (4Q and 2027) will be important for the next leg of the stock.”
BMO is one of nine Buys on the stock. The other two analysts covering AVY call it a Hold.
8. Abbott Laboratories
- Sector: Healthcare
- Market cap: $196.6 billion
- Dividend yield: 2.2%
- Consensus analyst rating: 1.54 (Buy)
Abbott Laboratories (ABT) is a large healthcare firm that develops, makes, and sells medical devices, diagnostic products, nutritional products, and generic pharmaceuticals. Among other things, it’s responsible for FreeStyle (and FreeStyle Libre) glucose monitors, Pedialyte hydration products, Similac formulas, PediaSure children’s nutritional products, and BinaxNow COVID-19 antigen tests. It’s also the owner of Cologuard screening tests following the March 2026 closure of its acquisition of Exact Sciences.
Medical devices are Abbott’s biggest breadwinner at nearly half of revenues, and they’ve been a key driver of growth of late, producing some of the company’s best year-over-year comparisons.
Related: 11 Best Vanguard Funds for the Everyday Investor
“Abbott’s continued growth on the MedTech side, disciplined M&A, and margin leverage over time buoy our constructive stance on the name,” say Oppenheimer analysts, who rate the stock at Outperform. “The relative buffers provided by the different business segments, ~2% dividend yield, and potential for margin expansion form the basis of our constructive stance on the name.”
Abbott fell into bear-market territory earlier in 2026, but the stock is recovering as a few headwinds (including weakness in nutrition) start to wane. The pros remain bullish, with ABT commanding 23 Buys against five Holds and no Sells.
“Our rating on Abbott Laboratories is Buy and underpinned by the company’s upbeat outlook,” says Argus Research analyst David Toung. “The company sees stronger topline growth in the second half of 2026, driven by cancer diagnostics, cardiovascular, and an improving Nutritional Products segment. Abbott plans three product launches in Cardiovascular as well as expanded reimbursement coverage for FreeStyle Libre.”
Related: 7 Best Vanguard Dividend Funds [Low-Cost Income]
“We are optimistic on an organic growth recovery through ’26, as we see underlying growth drivers as intact to work back to a high-single-digit growth profile in 2027 and fewer headwinds plus increasing [Exact Sciences] contributions in 2027,” add Jefferies analysts, who also rate the stock at Buy. “We see ABT as a top-quality, well-run franchise and view the stock’s valuation as attractive. ABT is a show-me story but with a good set of businesses and pipeline that we think can recover with better execution.”
Abbott is not only a S&P 500 Dividend Aristocrat (S&P 500 companies that have raised their dividends for at least 25 consecutive years), but it’s a Dividend King (the same thing, but for at least half a century). Thanks to a 7% hike, to 63¢ per share, announced in December 2025, ABT now boasts 54 years of uninterrupted dividend growth. The distribution itself dates back more than a century, to 1924.
For now, a safe payout ratio of less than 45% of 2027’s projected earnings provides little reason to think both streaks won’t continue.
Make sure you sign up for The Weekend Tea, our free weekly newsletter that over 10k monthly readers use to level up their money know-how.
7. Hasbro
- Sector: Consumer discretionary
- Market cap: $17.0 billion
- Dividend yield: 2.4%
- Consensus analyst rating: 1.50 (Strong Buy)
Toys are a part of everyday life that has endured for eons. The toys might change—wooden dolls have given way to kids’ tablet computers and chemistry sets—but the desire to make a business out of entertaining children isn’t going anywhere.
Hasbro (HAS) is one of the world’s largest toy and gamemakers, offering action figures, dolls, trading cards, plush products, preschool toys, play sets, and other consumer products across dozens of both its own brands as well as third parties it has contracted with. Indeed, just a partial rundown of Hasbro’s biggest brands include the likes of Star Wars, Magic: The Gathering (MTG), Play-Doh, Transformers, Peppa Pig, Final Fantasy, The Lord of the Rings, The Avengers, Nerf, and Monopoly.
Related: The 10 Best Vanguard Index Funds You Can Buy
Hasbro appears to be clawing its way out of a prolonged earnings slump, posting 11 consecutive quarters of profit growth. That hasn’t come without bumps—shares slumped in May after the company beat Q1 earnings estimates but provided conservative guidance amid high oil prices and an uncertain tariff situation. But the shares started coming back around in July thanks to strength in the firm’s Wizards of the Coast (responsible for MTG) and Digital Gaming arms, then were bolstered further by a Street-beating Q3.
“Looking ahead, 2027 is shaping up to be a strong year. Management expects Magic to grow mid- to high-single-digits in 2027 on top of ~high-teens+ growth in 2026 (and ~60% growth in 2025),” writes Xian Siew, BNP Paribas Equity Research Senior Analyst, who rates the stock at Outperform (equivalent of Buy). “Growth should be supported by player growth, distribution, and scaling supply capacity. We also flag upcoming new sets such Darkhold Destiny. For the Wizards segment, mgmt. expects margins to be in the high-30% range (low end of longer-term guide of high-30% to low-40%) due to software depreciation related to video games, but this should ease as we expect ’27 is peak video game spend.”
Siew represents one of 12 Buy-equivalent calls on HAS stock, versus just one Hold and one Sell, putting it among the best dividend stocks to buy right now.
Speaking of dividends: Hasbro’s cash distribution has either remained steady or grown every year for a quarter-century. Its current 70¢ quarterly dole comes out to an above-average yield of 2.4%, and represents only 40% of 2027’s projected earnings—a plenty comfortable cushion that should at least allow Hasbro to maintain the dividend at current levels, if not modestly raise in the future.
Related: 12 Best Vanguard ETFs You Can Buy [Build a Low-Cost Portfolio]
6. Bank of America
- Sector: Financials
- Market cap: $350.5 billion
- Dividend yield: 2.6%
- Consensus analyst rating: 1.48 (Strong Buy)
Bank of America (BAC) is one of the world’s largest banks, serving roughly 70 million Americans through 3,800 branches and 15,000 ATMs across 39 states. However, BofA is much, much more than its consumer business—it also provides financial products and services for small and midsized businesses, large corporations, institutional investors, and even governments. Its offerings range from checking and savings accounts to commercial loans, trade finance, treasury management, and securities clearing.
Related: The 10 Best Dividend ETFs for the Rest of 2026
BAC shares are well in the red amid a roller-coaster year most recently punctuated with a $1.2 billion anti-money-laundering fine announced in mid-October. spent most of the year in the red, but they rebounded during the summer to flip to single-digit gains. Relatively volatile markets have helped push trading revenues higher, loans are growing, and the company’s net interest margin (NIM) picture is improving.
“We believe the penalty represents a one-time earnings charge rather than an ongoing change to the underlying earnings power of the franchise,” say Jefferies analysts, who rate the stock at Buy. “Our Buy rating reflects BAC’s strong [net interest income] outlook, supported by fixed-asset repricing and expectations for disciplined expense growth that should drive durable operating leverage. BAC’s strong consumer deposit base is a positive differentiator, and we also value its solid credit quality. We believe improving [return on tangible common equity] should help narrow BAC’s valuation gap versus its closest peer, [JPMorgan Chase].”
Related: 10 Best Dividend Mutual Funds You Can Buy Now
“A strong pipeline in advisory supports our upward revision to Global Banking estimates in 2027 and 2028, as expectations imply a more pushed timeline,” adds Citi analyst Benjamin Gerlinger (Buy). “We revised expenses upwards driven by higher personnel cost growth rate. … We see continued NII growth as a tailwind supported by an increase in [commercial and industrial] loans; a low loan-to-deposit ratio creates NII upside with a more productive balance sheet.”
Analysts are plenty bullish on this Big Four bank, offering up 19 Buy ratings against just three Holds and no Sells. Bank of America has raised its cash distribution by 78% between 2020 and today. Most recently, it announced a stellar 14% hike, to 32¢ per share, effective as of the September 2026 payout. That dividend is very well-covered at about 25% of 2027’s expected earnings.
Related: The 7 Best Mutual Funds for Beginners
Need Help Picking Stocks? Consider These Top-Rated Services
|
Best Introductory Stock Picking Service
|
Best Overall Stock Research Service

|
Best Free Stock Charting Tool
|
Best Active Trader Stock Service

|
|
Primary Rating:
4.7
|
Primary Rating:
4.8
|
Primary Rating:
4.5
|
Primary Rating:
4.7
|
|
$99/yr.*
|
Premium: 7-day free trial, then $269/yr. ($30 discount)* Pro: 1 month for $89, then $2,149/yr.**
|
Prices range from $12.95/mo. to $199.95/mo. depending on tier. (Free trial and $15 off when you sign up with our link.)
|
TI Basic: 1,068/yr. ($833 first-year price with code YATI22.) TI Premium: $2,136/yr.* ($1,538 first-year price with code YATI28.)
|
5. Xcel Energy
- Sector: Utilities
- Market cap: $51.7 billion
- Dividend yield: 3.0%
- Consensus analyst rating: 1.45 (Strong Buy)
Xcel Energy (XEL) is a regulated utility provider that serves 3.9 million electricity and 2.2 million natural gas customers across eight states, primarily in the Midwest. It generates electricity through natural gas, oil, wind, nuclear, hydroelectric, solar, and other energy sources. The company also develops and leases natural gas pipelines, as well as storage and compression facilities.
Related: 11 Best Investment Opportunities for Accredited Investors
Like many utility companies, XEL has seen its fortunes improve alongside artificial intelligence (AI) companies’ ravenous demand to churn out power-hungry datacenters. But other drivers are powering Xcel ahead.
“Sitting in a favorable overlay of strong renewables resources, growing demand, and pragmatic regulation across most of the company’s Upper Midwest to Colorado/Texas footprint, XEL offers a ‘many ways to win’ dynamic with growth and upside drivers not narrowly tied to any one theme,” says Truist’s Richard Sunderland, who is one of 18 Buys on the stock (against one Hold and one Sell).
More recently, he wrote that “with 10%+ 2027-2030 EPS growth outlined on XEL’s call, a continued upside skew to growth, and increasing financing flexibility late in the plan period, we see the full growth picture offered on today’s call as a clear positive in confirming double-digit growth and drivers to extend this attractive growth.”
Related: 8 Best Stock Picking Services, Subscriptions, Advisors & Sites
“We are favorable on nuclear generation, which can further save costs and receive favorable regulatory outcomes. In fact, recent favorable electricity regulatory increases have helped offset older decisions in which some customers paid rates tied to wholesale prices,” adds Argus Research analyst Marie Ferguson (Buy). “The company should expect to see stronger demographics as the economy improves and Denver remains a popular growth region. XEL is projected to see above-average growth in data center demand by 2028.”
Xcel also offers a stereotypically above-average dividend yield of 3% right now; Argus points out that “the company has grown its dividend faster than some peers,” too. That dividend reached 23 years of uninterrupted growth in February 2026, when XEL announced it would hike its payout by 4% to 59.25¢ per share. This amounts to just a little more than half of its 2027 earnings estimates, which is generally comfortable, certainly for a utility company.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
4. BlackRock
- Sector: Financials
- Market cap: $189.0 billion
- Dividend yield: 1.9%
- Consensus analyst rating: 1.39 (Strong Buy)
BlackRock (BLK) is one of the world’s largest asset management firms, boasting more than $15 trillion in assets across its many lines of business. Individual investors know it well for both its BlackRock mutual funds and closed-end funds (CEFs), as well as its iShares exchange-traded funds (ETFs). But it also manages money for institutional clients, including pension plans, foundations, charities, and insurance companies, among others.
Related: 5 Best Stock Recommendation Services [Stock Tips + Picks]
BlackRock has been in a broader uptrend since the depths of the Great Recession, and that has come alongside similar progression in both the company’s top and bottom lines. There have been a few hiccups along the way, of course, such as COVID and early 2026’s market downturn—but analysts frequently call out these dips as reasons to buy BLK shares.
It’s not in a dip right now, however. The company has flipped between red and black ink throughout 2026, but it’s currently sitting on low-double-digit gains this year. Wall Street believes there’s more to come, with 17 pros calling BLK a Buy against one Hold and no Sells.
Related: 8 Best T. Rowe Price Funds to Buy for the Rest of 2026
“We believe that BLK remains well positioned to deliver above-peer organic growth given its unmatched product breadth and distribution footprint (helped by its iShares franchise),” say Keefe, Bruyette & Woods analysts Aidan Hall and Kyle Voigt, who rate BlackRock’s stock at Outperform (equivalent of Buy). “Also, its scale and demonstrated ability to generate operating leverage bodes well for future earnings growth and operating leverage. The firm’s increasing alternatives presence and growing technology revenue stream add further breadth to what is already a diverse product/solutions offering.”
BlackRock has been a fount of dividend growth since the Great Recession, too. In the past decade alone, BLK has managed to average 10% annual dividend growth. Its most recent hike, announced in early February 2026, was a stout 10% bump to $5.73 per share. Still, a payout ratio of just 35% of 2027 profit estimates should keep investors plenty confident in the dividend’s health and its ability to keep growing.
Featured Financial Products
3. Targa Resources
- Sector: Energy
- Market cap: $58.5 billion
- Dividend yield: 1.9%
- Consensus analyst rating: 1.36 (Strong Buy)
Targa Resources (TRGP) deals in the midstream energy market segment. Alongside its subsidiary, Targa Resource Partners LP, it owns a wide array of gathering, processing, logistics, and transportation assets across numerous natural resource plays, including the Permian Basin, Bakken Shale, Anadarko Basin, and the Gulf of Mexico, among others. The Permian Basin is arguably Targa’s biggest growth driver; roughly 3 in 5 lower-48 U.S. shale rigs are located there, and about 80% of Targa’s natural gas inlet volumes are sourced from there.
Targa had a rocky decade or so of trading following its public listing in 2010. But it has roughly quintupled over the past five years, including a 45% surge in 2026, and the analyst community remains wildly bullish about this energy name: Twenty-one Buys dwarf just one Hold call and no Sells, making TRGP one of the market’s best dividend stocks to buy right now.
Much of this can be attributed to Targa’s positioning in the Permian.
Related: 8 Best Schwab Index Funds for Thrifty Investors
“Targa maintains peer-leading earnings growth as one of the central infrastructure companies in the Permian and is simultaneously buoyed by an accelerating capital return profile, which we believe is likely to help sustain share momentum,” say Stifel analysts (Buy), who resumed coverage of the stock in September. “Targa is fully integrated across the [natural gas liquids] supply chain and is increasing natural gas exposure with a dominant Permian G&P position that in aggregate supports ~11% adjusted EBITDA [earnings before interest, taxes, depreciation, and amortization] growth through 2030, underpinned by over 90% fee-based earnings.”
Energy infrastructure stocks are a different breed. Many of them are master limited partnerships (MLPs), which are required to return a majority of their income to unitholders (shares in MLPs) in the form of distributions (dividend-like payments to shareholders that have different tax consequences). Targa is technically a corporation, though, so it pays dividends like a traditional stock.
In April, the company announced a 25% increase to its dividend, to $1.25 per share, which comes out to 40% of 2027. earnings projections. Management intends on recommending a 20% hike, to $1.50 per share, for 2027, which would bring that ratio to just below 50% and lift its yield to 2.2% at current prices.
Related: 11 Best Vanguard Retirement Funds [Save More in 2026]
2. CRH plc

- Sector: Materials
- Market cap: $65.2 billion
- Dividend yield: 1.7%
- Consensus analyst rating: 1.35 (Strong Buy)
Dublin-based CRH plc (CRH) is a leading global provider of building materials and construction solutions. It manufactures aggregates (crushed stone, sand, and gravel), cement, asphalt, ready-mixed concrete, and more. These materials are used for transportation networks, critical utilities, and commercial and residential building projects.
The company is getting bigger, too. CRH announced in June that it would acquire Dallas-based aggregates player Arcosa (ACA) for $8.5 billion in cash, which represented a 25% premium to Arcosa’s share price. The deal is expected to produce about $60 million in run-rate cost synergies in the first year following the deal close, $130 million in the second year, and $175 million in the third year.
Related: 10 Best Schwab Mutual Funds You Can Buy [Low Fees, $1 Minimums]
“The diversity of business will clearly help CRH in what is going to be a turbulent year of inflation particularly in Europe, solid demand in North America materials, and rising prices in many products,” says Truist Managing Director Keith Hughes (Buy). “The company’s recent M&A also helps cushion the inflation impact. The recent deals do show somewhat of a shift more towards water infrastructure (buying Axius) and away from outdoor living (sale of decking/mulch) in a trend that we believe will continue.”
More recently, Hughes pointed out that the company’s “Velocity” cost savings program is expected to yield $400 million in benefits. “CRH has the highest SG&A of most of its public materials peers, and reduction could clearly help at the minimum speed up decisions given overhead.”
At 22 Buys, one Hold, and zero Sells, it’s difficult to find better-rated dividend stocks than CRH right now.
The track record is a bit odd, however. While CRH has paid dividends for more than 50 years, the lion’s share of that time has been spent paying European-style interim-and-final dividends. But in 2024, the company switched to the quarterly system we’re used to in the U.S., and it has raised that payout twice since then, including a 5% improvement starting with the April 2026 distribution.
Related: 10 Best Schwab ETFs to Buy [Build Your Core for Cheap]
1. Devon Energy
- Sector: Energy
- Market cap: $46.6 billion
- Dividend yield: 3.0%
- Consensus analyst rating: 1.26 (Strong Buy)
Energy businesses are typically referred to by their “stream.” Upstream companies search for and extract oil, gas, and other raw energy resources; midstream companies transport, store, and sometimes process those resources; and downstream companies refine these resources into final products such as gasoline, diesel, and natural gas liquids (NGLs).
Devon Energy (DVN) is an upstream firm—an independent oil and natural gas exploration and production (E&P) firm that operates in some of America’s most potent locations, including the Delaware Basin, Anadarko Basin and Eagle Ford.
Related: The 10 Best Dividend Stocks for Beginners in 2026
DVN has also become much bigger thanks to the company’s May 2026 merger with Coterra Energy. Devon says that on a pro forma basis, the combined company’s 2025 daily production was about 548,000 barrels of oil, 348,000 barrels of natural gas liquids, and about 4.3 billion cubic feet of natural gas.
E&P companies are more beholden to commodity prices than the other “streams,” so as oil and nat gas prices go, so go their shares. Their differences boil down to operational efficiency, and Devon Energy is among the best, according to Wall Street analysts, who as a group have 27 Buys on the stock against one Hold and no Sells. For now, that means Devon is the very best-rated dividend stock to buy within my selection universe.
Related: 8 Best Vanguard Retirement Funds for a 401(k)
“Devon reached a definitive path forward in 3Q,” say Stifel analysts (Buy). “After selling its Eagle Ford position for $3.5 billion in net after tax proceeds, management is retaining its current asset base after a review process, with a focus going forward on organic improvements, high-grading and growth investments in midstream and exploration. While knee-jerk reactions may prove negative with the loss of asset sale catalysts, the forward guide on $5.3 billion of [capital expenditures] in 2027 for 525 [million barrels per day] screens well, and investors can shift focus more toward fundamentals that we find compelling.”
Devon Energy celebrated the acquisition by announcing an $8 billion share buyback authorization and hiking its dividend by 33%, to 32¢ per share quarterly. That comes out to just 25% of this year’s expected earnings—a conservative payout ratio that offers plenty of dividend stability and room for expansion.
Want to talk more about your financial goals or concerns? Our services include comprehensive financial planning, investment management, estate planning, taxes, and more! Schedule a call with Riley to discuss what you need, and what we can do for you.
Related: 15 Stocks With a Holding Period of “Forever”
As even novice investors probably know, funds—whether they’re mutual funds or exchange-traded funds (ETFs)—are the simplest and easiest ways to invest in the stock market. But the best long-term stocks also offer many investors a way to stay “invested” intellectually—by following companies they believe in. They also provide investors with the potential for outperformance.
So if you’re looking for a starting point for your own portfolio, look no further. Check out our list of the best long-term stocks for buy-and-hold investors.
Related: These 10 Stocks Pay Us Each and Every Month
The vast majority of American dividend stocks pay regular, reliable payouts—and they do so at a more frequent clip (quarterly) than dividend stocks in most other countries (typically every six months or year).
Still, if you’ve ever thought to yourself, “it’d sure be nice to collect these dividends more often,” you don’t have to look far. While they’re not terribly common, American exchanges boast dozens of monthly dividend stocks.
Please Heart ❤️, Follow and Subscribe
Did you find this article helpful?
1. Click the Heart Button.
2. Follow WealthUpdate —-> https://flipboard.com/@WealthUpdate
3. Subscribe to Retire With Riley, our free weekly retirement planning newsletter.
Read More on WealthUpdate
- Estate Tax Exemption Jumps $480K for 2027
- Capital Gains Tax: What Is It, Rates, Home Sales + More
- 2027 Federal Tax Brackets Released: What Rate Will You Pay?
Disclosures
Plynk
All Plynk disclosures can be viewed here.