
More often than not, investors look to the stock market for investment gains from price appreciation. If a stock pays a dividend, that’s great … but chances are, that dividend will be a small portion of the overall performance profile.
High-yield dividend stocks are a different breed.
Companies that deliver an outsized amount of income give you returns you can fall back on when the market (and even the high-dividend stock itself) is struggling to tread water. These cash distributions also represent stability of sorts for retirees, whose budgets are typically fixed.
You don’t get something for nothing, of course, which is why you can’t just buy a company’s stock on headline yield alone. In fact, high yields can occasionally be a signal of underlying weakness in shares … and dividends aren’t guaranteed, either, so we have to be vigilant about determining those payouts’ viability.
Today, I’ll examine a group of high-yield dividend stocks that are showing more signs of fundamental quality than most. Not only do they deliver an average yield of more than 10%, but they also have the confidence of Wall Street’s analyst community.
Editor’s Note: Tabular data presented in this article is up-to-date as of Oct. 23, 2026.
Featured Financial Products
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
Table of Contents
Dividend Yields (And Dividend Safety)
Dividend yield is a simple calculation: annual dividend / price x 100. But this humble calculator crunch can mean a world of difference for investors, especially those reliant on income.
Let’s say you have a $1 million nest egg heading into retirement. If your portfolio yields 3%, you’ll collect $30,000 in dividend and interest income each year. If it yields 6%, though, you’ll collect $60,000—a dramatically higher number that would wildly alter your retirement calculus.
But dividend yields can be deceiving. You see, a company can get a very high annual dividend yield in two very different ways: the dividend growing very rapidly, or the share price falling very quickly. Here’s an example:
Alpha Corp., which trades for $100 per share, pays a 50¢-per-share quarterly dividend, or $2 across the whole year. It yields 2.0%. In a month, however, it yields 4.0%. Here are two ways that could have happened:
- Alpha Corp. doubled its dividend to $1.00 per share quarterly, good for a $4-per-share annual dividend. The share price stays the same. ($4 / $100 x 100 = 4.0%)
- Alpha Corp. kept its dividend at 50¢ quarterly ($2 annually), but its share price plunged in half to $50 per share. ($2 / $50 x 100 = 4.0%)
Understand that a company’s stock can plunge even if its financials are perfectly healthy; markets aren’t always rational. But very broadly speaking, if you’re comparing a company that just doubled its dividend to another company whose shares have been cut in half, you’d expect the former’s dividend health to be better.
That’s why you should always be mindful of dividend safety, but especially when it comes to high-yield dividend stocks. That’s because oftentimes, the dividend is a more significant contributor to returns than price, so any danger to the dividend could undermine your investment thesis.
So, that’s your goal: Determine whether the high-dividend stocks you buy are financially stable and can generate substantial profits and cash, which is how the dividend gets paid. Among other things, you’ll want to look at payout ratio, which determines what percentage of a company’s profits, distributable cash flow, and other financial metrics (depending on the type of stock) are being used to finance the dividend. Generally speaking, the lower the payout ratio, the more sustainable the payout.
How Does Dividend Growth Work?
Of course, yield is normally a function of what we know now—not how a business might change in the future. Many companies exhibit dividend growth over time.
There’s no universal rule about how companies might raise or reduce their payments, but generally dividend stocks tie these profit sharing plans to earnings growth.
In other words, if a company is making more profits, then they have more cash to spread around to shareholders. And if they hit a serious snag, there’s a chance dividends could be cut or eliminated to shore up finances.
Related: 7 Best Closed-End Funds (CEFs) Paying Us Up to 17.2%
What Is Yield on Cost?
When you look up a stock’s information, the dividend yield listed is based on the most recent dividend and the current stock price.
That yield is often actually different than the one current shareholders enjoy. That yield is called “yield on cost,” which is the payout based on what you paid, at the moment you invested.
Let’s say you buy a stock at $100, and it pays $1 per share. It yields 1.0% when you buy it ($1 / $100 x 100 = 1.0%).
In a year, that stock has doubled to $200 per share, and it also doubled its dividend to $2 per share. If you look up its information, its dividend is still 1.0% ($2 / $200 x 100 = 1.0%).
That’s not your yield on cost, however. You’re still receiving that higher dividend of $2 per share. But your cost basis is still the original $100 you bought the share at. So now, your yield on cost has doubled, to 2.0% ($2 / $100 * 100 = 2.0%)!
Earn a Dividend Match With Plynk**
- Plynk® is a dividend-friendly app that offers commission-free trades* on 5,000 stocks and more than 3,400 ETFs, and also supports mutual funds and cryptocurrencies.
- Plynk offers a cash match of 25% on dividend income that allows you to earn up to $250 extra each year.**
- Track your dividends and interest with Income Hub.
- Earn a 3.48% APY on uninvested cash.
- Plynk charges no account opening fees, and you can start investing for as little as $1.
- No account fees
- Smart design and smooth user experience
- Fractional shares
- Designed for beginning investors
- Virtual portfolios and simulated trading
- 25% dividend match
- Earn interest on uninvested cash
- One of the best automated investing programs we've seen (Steady Start)
- Elite educational resources and tools
- Lacks features such as options trading and advanced charting that more experienced traders prefer
8 High-Yield Stocks That Wall Street Analysts Love
Today, I’m going to look at several high-dividend stocks. All of them yield more than 5%—a level that’s more than four times what the S&P 500 offers currently, and that’s well above most traditional high-dividend ETFs. And several pay out much more than 5%, resulting in an average dividend yield of more than 9% across this list!
Every stock on this list also has a favorable view from Wall Street’s analyst community. The consensus analyst rating, courtesy of S&P Global Market Intelligence, is the average of all known analyst ratings of the stock, boiled down to a numerical system where …
- Less than 1.5 = Strong Buy
- 1.5-2.5 = Buy
- 2.5-3.5 = Hold
- 3.5-4.5 = Sell
- More than 4.5 = Strong Sell
In short, the lower the number, the better the overall consensus view on the stock. In the case of this list, I’ve included only stocks that have received a 2 or lower—in other words, clear-cut Buys in the analysts’ eyes.
Importantly: These are the best dividend stocks among companies that pay pretty high yields, but that doesn’t make any pick here a no-brainer slam dunk. They all have a blemish or two—whether it’s significant stock weakness of late, interest-rate risk, tight dividend coverage, or something else—but to the pros, at least, their high yields, relative value, and/or growth potential make the risk worth taking. So if you’re going to jump into high-yield investing, just make sure you do so with your eyes wide open.
Stocks are listed in reverse order of dividend yield, from the lowest-paying stock to the highest.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
8. Clearway Energy
- Industry: Renewable utilities
- Market capitalization: $3.8 billion
- Dividend yield: 5.9%
- Consensus analyst rating: 1.36 (Strong Buy)
We’ll start with one of the rarer business types out there: a “yieldco.”
In renewables and energy infrastructure, development companies work on research, development, and construction of projects like solar arrays, wind farms, or hydroelectric plants. Once those projects become operational, some companies opt to drop them into “yieldcos,” which exist to hold those assets. The assets throw off long-term, low-risk cash flows, much of which is shipped off to invsetors in the form of dividends.
Related: 10 Best Fidelity Retirement Funds [Low-Cost + Long-Term]
Clearway Energy (CWEN), for instance, is the yieldco for Clearway Group, which has some 32 gigawatts (GW) of projects in development, 17 GW of which is being developed specifically to supply datacenters via colocation arrangements. CWEN itself has 14 GW of generation capacity across roughly half the country. The vast majority of this capacity represents renewables like wind and solar, as well as battery storage.
“The growth opportunity in storage has been evident to the investment community, but direct stock exposure has been more of a challenge due to China’s role in the lithium-ion supply chain and execution challenges in integrator economics for FLNC,” says Truist Director Christopher Souther. “We continue to see [independent power producers] deploying storage, with CWEN (Buy) & ENLT (Buy) among the safest investments and best-positioned beneficiaries of accelerating storage additions, given their development pipelines, ability to pair solar with storage, and direct exposure to higher U.S. demand for dispatchable clean power.”
CWEN has a very convicted bull camp, with 13 analysts calling the stock a Buy, against just one Hold and no Sells. Among their favorite characteristics is Clearway’s generous and growing dividend, which has improved without interruption on a quarterly basis for years. That’s a unique trait even among Wall Street’s very best high-yield dividend stocks.
Related: 14 Best Investing Research & Stock Analysis Websites [2026]
7. Energy Transfer LP
- Industry: Energy midstream
- Market capitalization: $70.2 billion
- Distribution yield: 6.8%*
- Consensus analyst rating: 1.48 (Strong Buy)
Energy Transfer LP (ET) is one of the continent’s largest midstream energy firms. The Dallas-based MLP’s assets include roughly 140,000 miles of energy pipelines and other infrastructure across 44 states, and it’s responsible for transporting and storing crude oil, natural gas, NGLs, and refined products. Its additional assets include Lake Charles LNG Company; incentive distribution rights from, and a 15% stake in, Sunoco LP (SUN); and a 32% stake in USA Compression Partners LP (USAC).
Midstream companies are considered a more stable way to invest in energy given that, rather than their fates living and dying by the price of oil or gas like exploration-and-production companies, they instead simply make money when commodities flow through their systems. In that way, they’re something of a toll taker, and they redistribute much of that cash in the form of distributions.
Related: The 10 Best Dividend Stocks for Beginners [2026]
“We continue to favor ET’s dominant energy infrastructure footprint and believe the partnership is well positioned to grow over the last several years,” say Stifel analysts Selman Akyol and Timothy O’Toole, who rate Energy Transfer’s units at Buy. “While capital expenditures will likely remain elevated in the near-term, we believe ET can maintain an attractive financial position and continue to modestly grow its distribution. We believe investors will be well served by owning ET as demand for U.S. energy increases around the globe.”
UBS analyst Manav Gupta (Buy) is also optimistic about Energy Transfer development projects such as its expansion in America’s Southwest. “Desert Southwest will provide reliable economic supplies of natural gas to support the long-term energy needs for utilities and energy providers in the region driven by population growth, high-tech industry demand and data center expansion,” he says.
This promise has 18 of ET’s 21 covering analysts in the Buy camp. The three dissenters call ET a Hold.
As for the distribution? For those who don’t remember, Energy Transfer chopped its payout in half in 2020 during the depths of COVID. However, it started a quarterly distribution growth streak in 2022—one that has persisted for 20 consecutive quarters as of its October 2026 hike.
Related: Dividend Kings: The Full List of American Dividend Royalty
Energy Transfer says it’s committed to growing the distribution even more going forward, though it’s taking an understandably cautious approach, targeting 3% to 5% annual growth. Distribution coverage is plenty adequate; estimates for distributable cash flow are just a little less than twice what it needs to afford its payout.
You’ll probably notice that I’ve been using some unfamiliar terminology. That’s because ET is a master limited partnership (MLP), which trades like a stock but is internally organized differently. It also uses a few different terms. For instance, shares are “units,” and it pays a dividend-esque “distribution” that can be something of a hassle from a taxation standpoint, especially for novices.
* Distribution yield is calculated by annualizing the most recent distribution and dividing by unit price. Distributions are like dividends, but they are treated as tax-deferred returns of capital and require different tax paperwork.
Featured Financial Products
6. Alpine Income Property Trust
- Industry: Net-lease REIT
- Market capitalization: $291.7 million
- Dividend yield: 6.9%
- Consensus analyst rating: 1.73 (Buy)
Alpine Income Property Trust (PINE) is a real estate investment trust (REIT) that specializes in single-tenant “net-lease” properties. Its portfolio of 130 properties in 31 states is leased out to retailers, pharmacies, grocery stores and more—tenants include Lowe’s (LOW), Dick’s Sporting Goods (DKS), Walmart (WMT), and Best Buy (BBY).
Related: 10 Best Dividend Mutual Funds You Can Buy Now
Net-lease arrangements are different from traditional leases. They typically require tenants to be responsible for taxes, insurance, and maintenance—thus, all rent is “net” of those expenses. As a result, net-lease REITs’ results tend to be a little more regular and predictable compared to traditional REITs. It also has a portfolio of mortgage originations, which it can use to bolster its income, but it’s a higher-risk, lower-quality business.
“This steady guidance and various operational updates, including unchanged quarter-over-quarter occupancy of 99.5%, the extending of PINE’s external growth runway via aforementioned newly disclosed ATM equity raising, and the newly disclosed sourcing of a somewhat evenly mixed collection of high-yielding loan investments and lower-cap-rate net lease transactions during 2Q26—with the cap rate on property acquisitions in line with FY25 activity—all seem to reflect continued steady execution for PINE,” B. Riley Securities analyst John Massocca, who rates the stock at Buy, wrote after the company’s most recent earnings report.
Related: The 13 Best Mutual Funds for the Rest of 2026
Like most REITs, Alpine has been battered by the Federal Reserve’s recent rate hike (and investor expectations for more). But that has bolstered the yield on its dividend, which has been dutifully raised since the company came public in 2019. The most recent hike, in February 2026, put the distribution at 30¢ per share, which annualizes to a yield of almost 7% at current prices.
There’s naturally higher risk just given Alpine’s small size relative to most of the other names on this list, but its substantial payday and growing business put it among the best high-yield dividend stocks to buy now.
Related: 8 Low- and Minimum-Volatility ETFs for Peace of Mind
Need Help Picking Stocks? Consider These Top-Rated Services
|
Best Introductory Stock Picking Service
|
Best Overall Stock Research Service

|
Best Free Stock Charting Tool
|
Best Active Trader Stock Service

|
|
Primary Rating:
4.7
|
Primary Rating:
4.8
|
Primary Rating:
4.5
|
Primary Rating:
4.7
|
|
$99/yr.*
|
Premium: 7-day free trial, then $269/yr. ($30 discount)* Pro: 1 month for $89, then $2,149/yr.**
|
Prices range from $12.95/mo. to $199.95/mo. depending on tier. (Free trial and $15 off when you sign up with our link.)
|
TI Basic: 1,068/yr. ($833 first-year price with code YATI22.) TI Premium: $2,136/yr.* ($1,538 first-year price with code YATI28.)
|
5. CTO Realty Growth
- Industry: Retail and mixed-use REIT
- Market capitalization: $741.5 million
- Dividend yield: 7.8%
- Consensus analyst rating: 1.00 (Strong Buy)
CTO Realty Growth (CTO) is a retail-oriented REIT that holds a tight portfolio of 21 properties spanning 5.8 million square feet across seven Southeast and Southwest states. It also owns a roughly 13% interest in the aforementioned Alpine Income Property Trust.
It divides its portfolio into three types of properties: grocery-anchored retail, retail “power centers,” and retail-focused lifestyle and mixed-used properties. Its properties are also located in and near affluent areas, many of which are benefitting from booming population growth. The portfolio average household income within five miles is $124,000.
Related: 10 Best Schwab ETFs to Buy [Build Your Core for Cheap]
CTO Realty Growth has actually existed in one form or another since 1902, and it has been paying dividends for more than half a century. But it really put the pedal down on dividend payments when it converted into a REIT in early 2021. The company paid 12¢ per share across 2019; in 2025, it paid $1.52. The stock has largely responded, delivering a total return (price plus dividends) of 85% since Feb. 1, 2021, versus just a bit more than 30% gains for the REIT benchmark.
The few analysts who cover CTO Realty Growth see more good times ahead. Indeed, they’re unanimously bullish—all five call the stock a Buy. Thus, while CTO shares don’t have the largest dividend on this list, they’re easily the best-rated of our high-yield dividend stocks.
But the dividend is still high and in great shape. CTO recently provided full-year 2026 adjusted funds from operations (AFFO, a vital REIT profit metric that also speaks to dividend coverage) guidance of $2.21-$2.25 per share, which would easily cover the company’s $1.52 in annual distributions.
4. Rithm Capital
- Industry: Mortgage REIT and alternative asset management
- Market capitalization: $5.2 billion
- Dividend yield: 10.7%
- Consensus analyst rating: 1.36 (Strong Buy)
Most REITs that you read about tend to be “equity REITs,” which deal in physical real estate. Specifically, they own (and sometimes operate or manage) properties, whether that’s apartments, office buildings, hotels, warehouses, you name it.
But “mortgage REITs” deal in paper real estate. That typically takes the form of residential and/or commercial mortgages, as well as mortgage-backed securities (MBSes). An mREIT will borrow money at short-term interest rates. It will take that money and buy mortgages, MBSes, and/or other mortgage-related securities. It will then earn income from the interest generated by these products—and use much of this profit to pay dividends to its shareholders. In fact, mREITs tend to have higher dividend yields than their traditional real estate cousins.
Related: 11 Best Investment Opportunities for Accredited Investors
Rithm Capital (RITM) is technically a mortgage REIT, though it looks much different than the other mREITs that appear later in this list. This “hybrid” mREIT has numerous businesses, including alternative asset management. RITM invests in residential mortgages loans, consumer loans, single-family rentals, mortgage servicing rights (MSRs), residential transitional loans, secured lending and structured products, and commercial real estate.
Ever since the 2020 financing crisis, the company has transformed its business model, growing its mortgage servicing business while also acquiring a variety of debt-related investment opportunities. It continues to be acquisitive, too, completing deals to acquire an alternative asset manager (Crestline Management) and an owner-operator of Class A properties (Paramount Group) in December 2025.
“The stock has been down lately due to growing concerns in the private-credit sector. However, we believe that the market is lumping alternative managers together and ignoring RITM’s other business lines,” writes Argus Research analyst Kevin Heal (Buy). “It continues to grow its mortgage-servicing business, refine its mortgage-recapture process with recent partnerships, and take advantage of new debt-related investment opportunities.”
Related: 5 Best Tech Dividend Stocks [According to the Pros]
Indeed, net servicing revenues helped push RITM to a stronger-than-expected third-quarter report, announced just a few hours prior to this writing.
The pros love the new-look Rithm Capital; every one of the 11 analysts covering the stock call it a Buy. “We believe RITM remains a best-in-class REIT that has diversified its revenue streams and has consistently delivered strong earnings comfortably above its dividend,” add Keefe, Bruyette & Woods analysts, who rate the stock at Outperform.
As for the dividend: While it has remained stagnant for years, it still translates into a double-digit yield at current prices.
Make sure you sign up for The Weekend Tea, our free weekly newsletter that over 10k monthly readers use to level up their money know-how.
3. Trinity Capital
- Industry: BDC
- Market capitalization: $1.6 billion
- Dividend yield: 12.5%
- Consensus analyst rating: 1.78 (Buy)
Trinity Capital (TRIN) belongs to another high-yielding acronym industry: business development companies (BDCs).
Fun fact: Congress is actually responsible for the creation of real estate investment trusts, which were brought to life in 1960 with a mandate to return at least 90% of their taxable income back to shareholders as dividends (in exchange for favorable tax treatment). Well, 20 years later, in the hopes of spurring investment in smaller businesses, Congress went back to the same playbook and created BDCs—with the same dividend mandate.
Trinity is an alternative asset manager that focuses on five specific business verticals: technology lending, equipment financing, life sciences, asset-based lending, and sponsor finance.
Loans make up the majority (75%) of the portfolio by investment type, and floating-rate loans make up a large (82%) and growing percentage of that part of the debt portfolio. Another 14% is made up of equipment financings, and the rest is equity and warrants. Its 190 portfolio companies include the likes of launch service and spacecraft component provider Rocket Lab (RKLB), non-alcoholic craft brewer Athletic Brewing, and arthroplasty-focused medical device firm Shoulder Innovations (SI).
Related: 7 Best Vanguard Dividend Funds [Low-Cost Income]
B. Riley Securities analyst Sean-Paul Adams has a Buy rating on shares, citing the company’s investment-grade rating from Moody’s, SBIC fund approval, record origination levels and increased equipment finance vertical demand.
“Record fundings of $619 million and platform assets under management of $3.2 billion (up 36% Y/Y) keep origination momentum and the fee platform as the primary earnings drivers, in our view,” he says. “TRIN’s strong yield, originations momentum, and platform expansion provide meaningful near-term upside potential, in our view.”
Adams is one of seven Buy-equivalent ratings on the stock, opposed by just one Hold and one Sell.
Trinity’s sky-high dividend yield (currently more than 11%) is blunted a little bit by a lack of payout growth. The company came public in early 2021, and raised its dividend on a quarterly basis through the end of 2023, but it has kept that distribution level ever since.
That said, Trinity started 2026 by joining the ranks of monthly dividend stocks, so investors will be getting paid much more frequently now. That, as well as the mammoth payout and high ratings from analysts, are more than enough to put Trinity among the best high-yield dividend stocks to buy now.
Related: 5 Best Stock Recommendation Services [Stock Tips + Picks]
2. Millrose Properties
- Industry: Residential REIT
- Market capitalization: $4.0 billion
- Dividend yield: 13.2%
- Consensus analyst rating: 1.33 (Strong Buy)
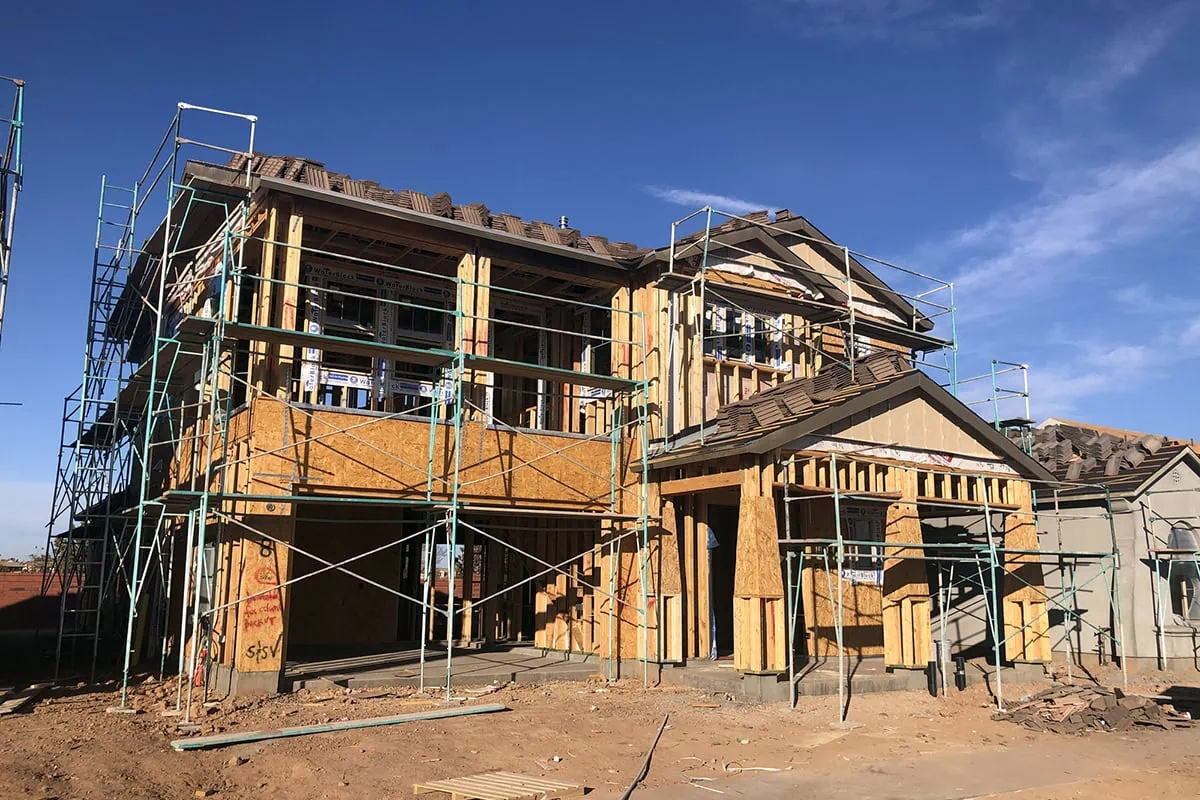
Millrose Properties (MRP) isn’t a run-of-the-mill residential REIT. In fact, it’s a trailblazer.
Millrose was a part of homebuilder Lennar (LEN) until it was spun off in 2024. It buys and develops residential land, then turns around and sells its finished homesites back to Lennar and other homebuilders via options contracts at set fees.
Because of its relative newness and novelty, MRP doesn’t exactly have a crowded coverage base. But most of the few Wall Street analysts assigned to the company like what they see: the stock garners five Buys, one Hold, and no Sells. The bull camp includes Citi’s Nick Joseph, who rates the stock at Buy and is warming on the company’s landbanking partnership with real estate development company JPI.
Related: 8 Best-in-Class Bond Funds to Buy
“We were initially skeptical of MRP’s new multifamily landbanking facility with JPI, as: 1) a large developer would only enter a new facility if it lowered financing costs, enabled new product types, or reduced risk; 2) multifamily construction lending is competitive at lower spreads unless underwriting higher LTVs; and 3) MRP lacks a competitive advantage in underwriting multifamily inputs (e.g. rent levels, cap rates) compared to its real-time for-sale data,” he writes. ” However, in speaking with large apartment developers, institutional capital focused on multifamily landbanking is scarcer than we assumed, and developer equity costs are likely higher than MRP’s option yield—creating an opportunity for MRP to selectively offer permanent financing between traditional debt and equity.”
Perhaps most noteworthy is an extremely aggressive dividend. The company kicked off its program in April 2025 with a prorated 38¢ quarterly distribution, which became 69¢ in July. That dividend has grown in every quarter since; the most recent 79¢ payout comes out to a 13%-plus yield at current prices.
Related: The 7 Best Gold ETFs You Can Buy
1. Dynex Capital
- Industry: Mortgage REIT
- Market capitalization: $2.7 billion
- Dividend yield: 18.7%
- Consensus analyst rating: 1.83 (Buy)
Dynex Capital (DX) is the longest-tenured mREIT, founded in 1987. And it’s explicitly an “agency” mREIT, which means it deals in mortgages and MBSes from government agencies such as Freddie Mac and Fannie Mae. In fact, its portfolio is 97% agency residential MBSes (RMBSes), and most of the remainder is agency commercial MBSes (CMBSes).
Keefe, Bruyette and Woods, whose analysts rate Dynex at Outperform, was broadly bullish on agency MBS sectors heading into 2026. Agency MBS spreads tightened in the back half of 2025, but KBW believed spreads would benefit from a steeper yield curve as the Federal Reserve cut rates. The year hasn’t played out that way so far, but KBW still remains upbeat about DX.
Related: 11 Best Alternative Investments [Options to Consider]
“Management noted that roughly 80% of the Q3 decline in book value was driven by widening spreads,” KBW recently wrote after the company’s third-quarter earnings report. “DX largely maintained its portfolio during Q3 as spreads widened and book value declined, which positions the company to generate higher returns and be well positioned to recover book value if spreads tighten. … We view the shares as attractive given the current return and potential book value upside if spreads tighten.”
KBW is just one of a handful of analyst outfits that cover Dynex, which is typical for the mREIT industry. Still, among these few pros, the bulls are the majority—DX has four Buys versus two Holds and no Sells.
Dynex pays a monthly dividend, and a generous one at that—it yields almost 19% as I write this. However, mortgage REITs tend to have shakier dividend histories than traditional stocks and even equity REITs, and DX is no exception. Its dividend was hacked away by 85% between 2012 and 2020, to 13¢ per share monthly. But things are looking up recently: The company finally raised its dividend in mid-2024, to 15¢, then again in February 2025, to 17¢.
Still, that payout history is an important reminder that double-digit yields are hardly risk-free.
Related: 7 Best Real Estate Crowdfunding Sites + Platforms
Featured Financial Products
Do All Companies Pay Dividends?
Not all companies pay dividends. Some companies choose not to, while other companies cannot afford to.
As you can tell by this list, the best dividend stocks are normally slow-and-steady companies that have consistent operations. While it might be possible for a small software company or biotech firm to double its share price overnight, these companies rarely pay dividends because they don’t have much in the way of profits—and what they do have, they want to spend on other things, like research and development to continue growing.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
How Often Do Companies Pay Dividends?
The cycle of paying dividends is always different depending on the company. While it’s generally true that most U.S. corporations opt to pay their shareholders a dividend once per quarter, the dates aren’t fixed.
Specifically, one company might pay you on a January-April-July-October payment cycle while another opts for February-May-August-November.
Complicating things further, some companies pay dividends twice a year, some pay once a year, and some even pay “special” unscheduled dividends.
Related: Best Fidelity Retirement Funds for a 401(k) Plan
What Should Income Investors Look for in a Dividend Stock?
There are a host of things to consider when looking for the best dividend stocks.
First, and foremost, you should make sure you understand the underlying business and its strategy; just because a company pays a dividend doesn’t mean it can’t crash and burn.
If you generally like what you see, then you should consider the quality of the dividends including the history of payouts and the payout ratio as a portion of total earnings.
Then, you should consider the quantity of that dividend and the potential for future growth in payouts.
Want to talk more about your financial goals or concerns? Our services include comprehensive financial planning, investment management, estate planning, taxes, and more! Schedule a call with Riley to discuss what you need, and what we can do for you.
Related: The Best Dividend ETFs You Can Buy Right Now
We love exchange-traded funds (ETFs) because they can provide one-click access to hundreds, even thousands of stocks, while charging often minuscule fees.
One way to put that low-cost diversification to work? Collecting dividends. But trying to choose from literally hundreds of income-producing funds could take up a lot more time than you have. So let us help you narrow the field—check out our list of 10 top dividend ETFs.
Related: 10 Great Fidelity ETFs for Investors Who Want Something Different
Investors often look to exchange-traded funds (ETFs) for cheap, passive exposure to basic broader market indexes like the S&P 500.
But Fidelity’s ETF suite really shines because in addition to some of those plain-vanilla offerings, Fidelity also provides more tactical ways of tapping into specific corners of Wall Street. See what we mean by checking out our list of the best Fidelity ETFs.
Please Heart ❤️, Follow and Subscribe
Did you find this article helpful?
- Click the Heart Button.
- Follow WealthUpdate —-> https://flipboard.com/@WealthUpdate
- Subscribe to Retire With Riley, our free weekly retirement planning newsletter.
Read More on WealthUpdate
- 10 States Where Online Elder Fraud Runs Rampant
- 7 Best Fidelity Dividend Funds [Passive Income Picks]
- 9 Best Space ETFs for Investing’s Next Frontier
Disclosures
Plynk
All Plynk disclosures can be viewed here.