
Medicare’s Open Enrollment Period (OEP) for the 2027 plan year is rapidly approaching, and even if you don’t think you need to make any changes, you might need to think again.
If you’ve been happy with your plan in 2026, you might be lulled into letting the enrollment period pass by without a second look; generally speaking, Medicare coverage automatically renews if you do nothing. However, your plan might be changing next year, or it might not even be offered. And even if you ultimately decide to keep the same coverage, it’s important to note cost increases so you can adjust your retirement budget.
Let’s look at several notable Medicare changes taking effect in 2027 that beneficiaries should know to make the best decisions about their health coverage.
When Is Medicare’s Annual Open Enrollment Period?
Your Medicare Initial Enrollment Period (IEP) starts three months before you turn 65 and ends three months after the month you turn 65 (unless your birthday lands on the first of the month). Thankfully, that isn’t a person’s only chance to sign up for Medicare.
Medicare’s Open Enrollment Period (OEP) is every year from Oct. 15 through Dec. 7. Coverage selections made during this time take effect on Jan. 1 of the following year. Several actions can be taken throughout open enrollment, including:
- Switching Part C (Medicare Advantage) plans
- Changing Part D prescription drug plans
- Switching from Medicare Advantage to Original Medicare (or vice versa)
There are other Medicare enrollment periods as well, including the General Enrollment Period (GEP), Medicare Advantage Open Enrollment Period (MA-OEP), and Special Enrollment Periods (SEPs). Just be mindful of their deadlines and what each period allows for; you don’t want to end up on the hook for Medicare late enrollment penalties.
What Medicare Changes Are In Store for 2027?
Aspects of Medicare change each year, which means you might want to adjust your budget accordingly and/or switch plans.
“Even if you’ve been happy with the same Medicare coverage for years, you need to pay attention to what’s changing with your plan,” says Louisa Norris, health policy analyst for medicaresources.org, “Premiums, out-of-pocket costs, drug coverage, provider networks and plan availability can all change from one year to the next.”
Let’s dig into some of the 2027 changes beneficiaries need to pay attention to.
Related: 12 Costs ‘Original Medicare’ Doesn’t Cover
Medicare Part D Deductible and Out-of-Pocket Cap Increases
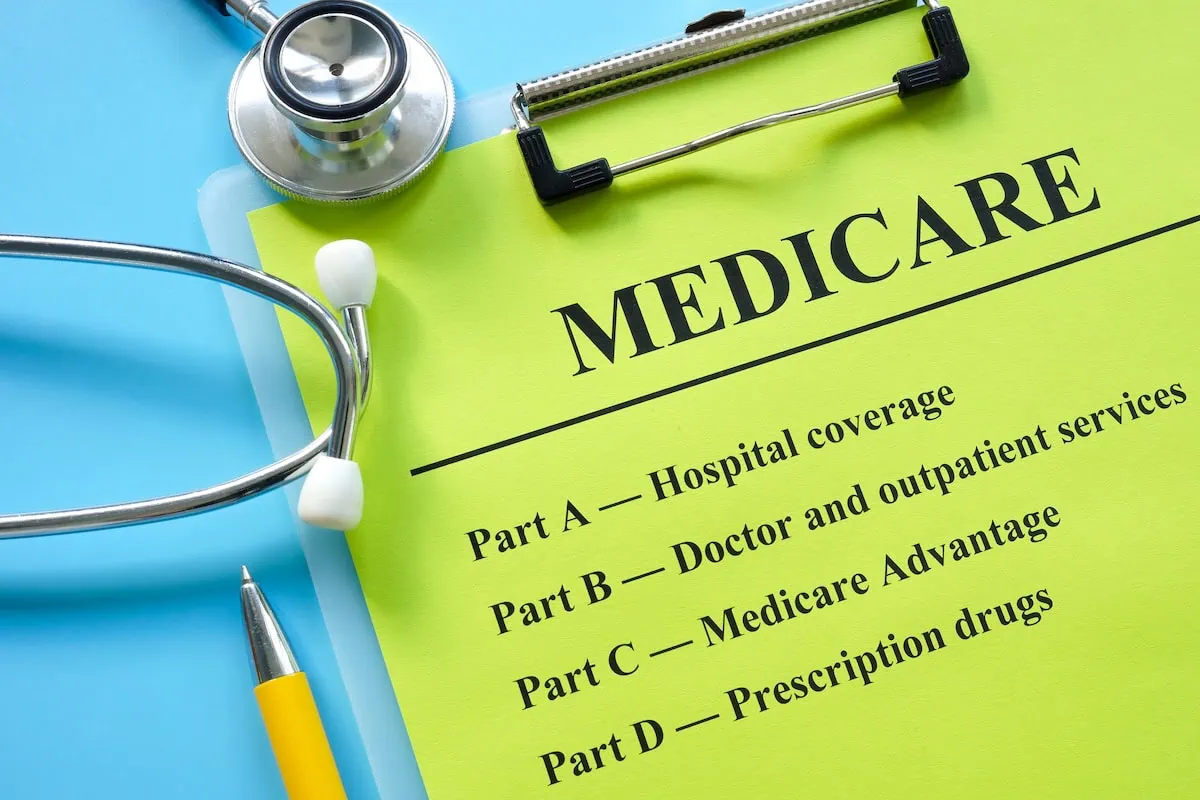
Medicare Part D is optional prescription drug coverage offered by private insurers. To be eligible for Part D, you must be enrolled in Medicare Part A or Medicare Part B.
The standard Medicare Part D deductible is going to increase to $700 in 2027 (up from $615 in 2026). The annual out-of-pocket cap is also increasing by $300, putting it at $2,400 for 2027.
Related: 9 Health Insurance Options for Early Retirees
Medicare Part D Premium Increases (Some People)
The Centers for Medicare & Medicaid Services (CMS) announced in late July 2026 the conclusion of the Part D Premium Stabilization Demonstration.
The demonstration’s goal was to stabilize standalone prescription drug plan (PDP) premiums and enrollment after changes to Part D in the Inflation Reduction Act. It gave extra subsidies to PDP plan sponsors, which in turn reduced the base beneficiary premium for enrollees.
Related: How to Plan for Healthcare Expenses in Retirement
The base beneficiary premium was lowered by $15, and the monthly premium increase was limited to $35, in the demonstration’s first year (2025).
This year, the base premium reduction was $10 and the premium increase was capped at $50. For 2027, the subsidies are gone altogether, which means some Part D enrollees might have higher premiums.
Make sure you sign up for The Weekend Tea, our free weekly newsletter that over 10k monthly readers use to level up their money know-how.
Additional Medicare-Negotiated Drug Prices Will Take Effect
Beginning Jan. 1, 2027, negotiated prices for another group of medications will take effect. This includes, among others …
- Trelegy Ellipta (asthma, chronic obstructivep pulmonary disease)
- Xtandi (prostate cancer)
- Ibrance (breast cancer)
- Linzess (chronic idiopathic constipation, irritable bowel syndrome with constipation)
- Otezla (plaque psoriasis, psoriatic arthritis, oral ulcers in Behçet’s disease)
It also includes several GLP-1 drugs, including Ozempic and Wegovy, which are covered under Part D for beneficiaries with certain health conditions (but not for weight loss).
While negotiated prices could lower costs for some beneficiaries, others might still reach the 2027 Part D out-of-pocket limit of $2,400 (up from $2,100 in 2026).
It’s important when comparing plans to check whether your preferred doctors or hospitals would be in-network and if your prescription medications are covered.
Note that a medication might appear on a plan’s formulary, but still need prior authorization or have other hurdles to jump through before the plan will cover it.
Related: 14 Ways to Lower Medicare Costs in Retirement
Empower Advisory Group offers a comprehensive wealth management service known as Personal Strategy Investment Services.
This managed account solution provides clients with discretionary investment management, personalized portfolio construction, and access to financial planning support.
Medicare Advantage Premium, Benefits, or Service Area Changes
Never assume your insurance will be exactly the same from one year to the next, and always read the Annual Notice of Change.
Some Part C (Medicare Advantage) insurers are adjusting their offerings for 2027. Part C users might have premiums added to plans that previously had $0 premiums.
Unfortunately, some Medicare Advantage plans are being discontinued altogether for 2027, while others are decreasing their presence. For instance, Humana announced this summer that its exit from some markets would affect around 600,000 members.
If you can no longer use your 2026 plan, you can either choose another Medicare Advantage plan or switch to Original Medicare. Those who jump ship to Original Medicare might have guaranteed-issue rights that let them purchase certain Medigap plans without medical underwriting even though Medicare’s annual enrollment period isn’t a Medigap open enrollment period.
In the majority of states, beneficiaries who voluntarily leave Medicare Advantage after their initial enrollment protections are over may be subject to medical underwriting to buy Medigap coverage.
“People often assume they can move freely between Medicare Advantage and Medigap during annual open enrollment, but that isn’t necessarily the case,” Norris says. “If your Medicare Advantage plan is terminating, you may have protections you wouldn’t otherwise have, so it’s important to understand all of your options before selecting replacement coverage.”
Related: Here’s How You Can Lose Medicare [And How You Won’t]