

The best and the worst real estate investment trusts (REITs) are separated by no small amount of quality. But that hasn’t mattered over the past month or so as America’s war against Iran has sent most assets into a tumble, real estate included.
REITs are a special business structure created by Congress that helped to democratize real estate investing, taking something that would ordinarily require hundreds of thousands of dollars in capital and making it so that anyone with 20 bucks in their pocket could get a piece—by purchasing shares in a publicly traded REIT, that is.
The advent of REITs didn’t take all the bricks off our shoulders, of course. The market can still throw curveballs at REITs, such as the Federal Reserve’s September rate increase, which sent real estate stocks reeling as it raised these companies’ borrowing costs and made their dividends a little less attractive compared to the relative safety of bonds. In other words: We still have to do our research and unearth the best REITs to buy if we want to maximize our real estate investments.
Let’s see if we can help out on that front. Today, I’ll review seven REITs that enjoy high ratings from Wall Street’s research community, including a new pick from the high-yield mortgage REIT industry. And true to REITs’ income-friendly nature, this list’s picks range in yield from 2x to 12x what the S&P 500 pays today.
Editor’s Note: Tabular information presented in this article is up-to-date as of Nov. 4, 2026.
Featured Financial Products
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
Table of Contents
What Are Real Estate Investment Trusts (REITs)?
A real estate investment trust, often referred to as a REIT (pronounced “reet”) is a unique class of investment. But if you break down each of those terms that make up the name of this asset, it will begin to make more sense.
The first two words (“real estate“) describe the business focus. REITs must derive at least 75% of their gross income from real estate-related income, and 75% of their assets must be real estate-related assets. And if you wonder why I keep saying “related,” that’s because REITs don’t always have to own physical properties—they can own real-estate related assets such as mortgages, too.
The world of REITs is broader than you might realize. REITs deal in all sorts of real estate, from common properties such as apartments, strip malls, and hotels, to less obvious properties such as concert venues, driving ranges, and telecommunications towers.
The last two words (“investment trust“) are important, too, in that they define how these companies are built and treat their investors.
There are certain thresholds that set REITs apart from conventional publicly traded company stocks. They must have at least 100 shareholders. They must have no more than 50% ownership resting in the hands of five or fewer investors. But perhaps the most important rule you need to know about real estate investment trusts is that they must pay at least 90% of taxable income to shareholders in the form of dividends each year. This demand for consistent income is a big reason many investors are drawn to REITs, particularly as a way to boost their retirement savings through regular dividends.
2 Types of REITs to Know
The REIT universe is sometimes divided into two distinct flavors: equity REITs and mortgage REITs. While they’re very closely related because both deal with real estate, their business models are extremely different.
And right now, amid a volatile interest-rate environment, the distinction is pretty important to acknowledge.
Let’s take a look at each type.
1. Equity REITs
If you’ve been investing for a while you’ve probably come across the word “equity” before. The term is shorthand for a direct ownership stake—and some investors even use the term “equities” to refer to the stock market as a whole, as shares of publicly traded companies are in fact equity stakes in individual businesses.
Equity REITs, then, are directly invested in real estate assets. They own or manage properties ranging from office buildings to shopping centers to apartment complexes, leasing that space and generating income from the rents. And publicly traded equity REITs allow you to enjoy in that exposure through their shares, which you can purchase through any traditional brokerage account.
Related: 8 Best High-Yield Dividend Stocks: The Pros’ Picks
2. Mortgage REITs
Mortgage REITs, on the other hand, don’t traffic in real estate properties—instead, they deal with debt. They finance real estate, operating less like a traditional REIT and more like a financial firm. This is done by either originating mortgages, or buying and selling those mortgages and related mortgage-backed securities. It also commonly involves borrowing heavily to then trade all that mortgage paper at scale. Their profits, then, tend to revolve around net interest income (NII): the difference between the interest revenue they generate and the financing costs on all their assets.
This fundamentally makes mortgage REITs riskier than equity REITs. After all, the 2008 financial crisis was caused in large part by financial firms borrowing heavily to invest in the debts of third parties. Particularly in the current interest rate environment, where borrowing is getting steadily more expensive all around, that’s a tough spot to be in.
That said, many mortgage REITs offer twice or even thrice the income potential of equity REITs. These dividends might be at risk of evaporating if things go south, but if they hold up, investors will be richly rewarded for looking beyond the conventional players on Wall Street.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
7 Best REITs to Buy Now
You already might be wondering how to decide between mortgage REITs or equity REITs, or whether you should invest in a small commercial real estate firm or a big industrial park operator. After all, there’s a great big world of real estate investing out there!
The answer is: There is no one right answer for everyone. With so many things on Wall Street, your unique risk tolerance and retirement planning needs are critical to deciding the best REITs to buy right now.
The following list should get you pointed in the right direction, however. All seven of these leading real estate investment trusts offer significant income and the potential for long-term upside if things pan out in 2026 and beyond.
All REITs listed in order of yield, from lowest to highest.
Related: How to Invest in Private Real Estate With Private Equity Funds
7. Equinix
- REIT industry: Datacenters
- Market capitalization: $100.5 billion
- Dividend yield: 2.0%
Equinix (EQIX) is the largest global data center and colocation provider for enterprise networks. In other words, Equinix is responsible for the actual server rooms that house all the bits and bytes that power all the content and software we offload to “the cloud” without really considering where the cloud is. That makes it a play on numerous technological megatrends, including cloud computing, yes, but also big data and artificial intelligence.
Related: 7 Best Closed-End Funds (CEFs) Paying Us Up to 17.8%
It’s a massive collective opportunity, and Equinix is one of the largest specialized firms in the space. This digital infrastructure provider boasts 529,000 interconnections to more than 11,000 customers, with a global reach of 77 metro areas in 36 countries. Those numbers will surely grow, with the company currently working on 46 projects in 32 markets across 22 countries.
“Equinix core retail-centric revenue growth is accelerating from a combination of volume, pricing, and better retention,” says Citi analyst Michael Rollins, who rates the stock at Buy. “We also believe the combination of stronger bookings and an accelerated [remaining performance obligation] balance leaves the door open for potentially further normalized recurring revenue growth acceleration in 2027.”
Related: 7 Best Vanguard Dividend Funds [Low-Cost Income]
Rollins is one of 30 analysts with a Buy-equivalent rating on the stock, which compares well to just five Holds and no Sells. Also ringing in after earnings was BNP Paribas Equity Research senior analyst Nate Crossett, who rates the stock at Outperform (equivalent of Buy).
“We would describe the quarter as generally sound with an increase in guidance,” he wrote in late October. “KPIs were sound with solid gross bookings (record level), and healthy pricing increases; churn was also notably low again. We remain supportive of shares as the commentary remains robust as it relates to overall demand.”
And despite what a relatively modest 2% yield might imply, Equinix has been downright aggressive in sharing its wealth with EQIX holders. The payout has roughly tripled over the past 10 years … it’s just that the shares have risen every bit as rapidly. Equinix’s stock is up 210% on a pure price basis in the past decade. Including dividends, shareholders have enjoyed a 270% total return.
6. Ventas
- REIT industry: Medical and senior housing
- Market capitalization: $46.3 billion
- Dividend yield: 2.4%
Ventas (VTR) is one of the market’s largest healthcare REITs, boasting about 1,450 properties in the U.S., Canada, and the U.K. This includes more than 850 senior housing communities, with the rest spread across outpatient medical, research, hospitals, long-term acute care, in-patient rehabilitation, and skilled-nursing facilities.
In short: Ventas sits at the intersection of a number of “necessary” healthcare properties.
Related: 8 Best High-Yield Dividend ETFs for Income-Hungry Investors
The broader real estate sector was hobbled during the COVID pandemic, but operators like Ventas were among the hardest hit. VTR in specific hemorrhaged roughly three-quarters of its value in less than two months as residents fled its senior housing and skilled-nursing facilities. That prompted its push into medical office real estate, which provided some stability. But the demographics that lifted senior housing and nursing operators certainly didn’t disappear, and now those properties are back in the spotlight.
Ventas isn’t resting on this tailwind, however; it’s also maximizing its senior housing properties by converting many of them from triple-net lease (NNN)—where tenants are responsible for taxes, maintenance, and insurance, and Ventas just cashes a check—to its more actively managed Senior Housing Operating Portfolio (SHOP). These SHOP properties have so far been a significant driver of net operating income (NOI).
Related: 8 Best-in-Class Bond Funds to Buy
“With an ever-aging population and a growing demand for senior living, the company has been returning to its core focus of private-pay senior living communities,” Argus Research analyst Marie Ferguson (Buy) says. “Ventas SHOP assets include independent living, assisted living, and memory care environments, many with high-end amenities which add pricing power. … A solid balance sheet and asset sales will help fund portfolio development. The SHOP segment has momentum and is expected to drive growth in 2026 from net operating income (NOI) growth and from the $2.5 billion in new investments in 2025.”
“Investment activity has been more robust than previously anticipated and is positively impacting the outlook,” JPMorgan analysts (Overweight, equivalent of Buy) added after the company’s Q3 report. “While management left its overall [same-store] NOI growth outlook unchanged (including unchanged property components), SHOP growth continues to be robust and is driving core growth.”
Ventas also was forced to slash its dividend during COVID, from 79¢ per share to 45¢, where it remained for years. However, in Q1 2025, the company finally delivered positive movement, announcing a 6.7% hike to the payout, to 48¢ per share. The company followed that up with an 8.3% boost to 52¢ in Q1 2026.
Make sure you sign up for The Weekend Tea, our free weekly newsletter that over 10k monthly readers use to level up their money know-how.
Featured Financial Products
5. Ryman Hospitality Properties
- REIT industry: Lodging and hospitality real estate
- Market capitalization: $9.3 billion
- Dividend yield: 3.5%
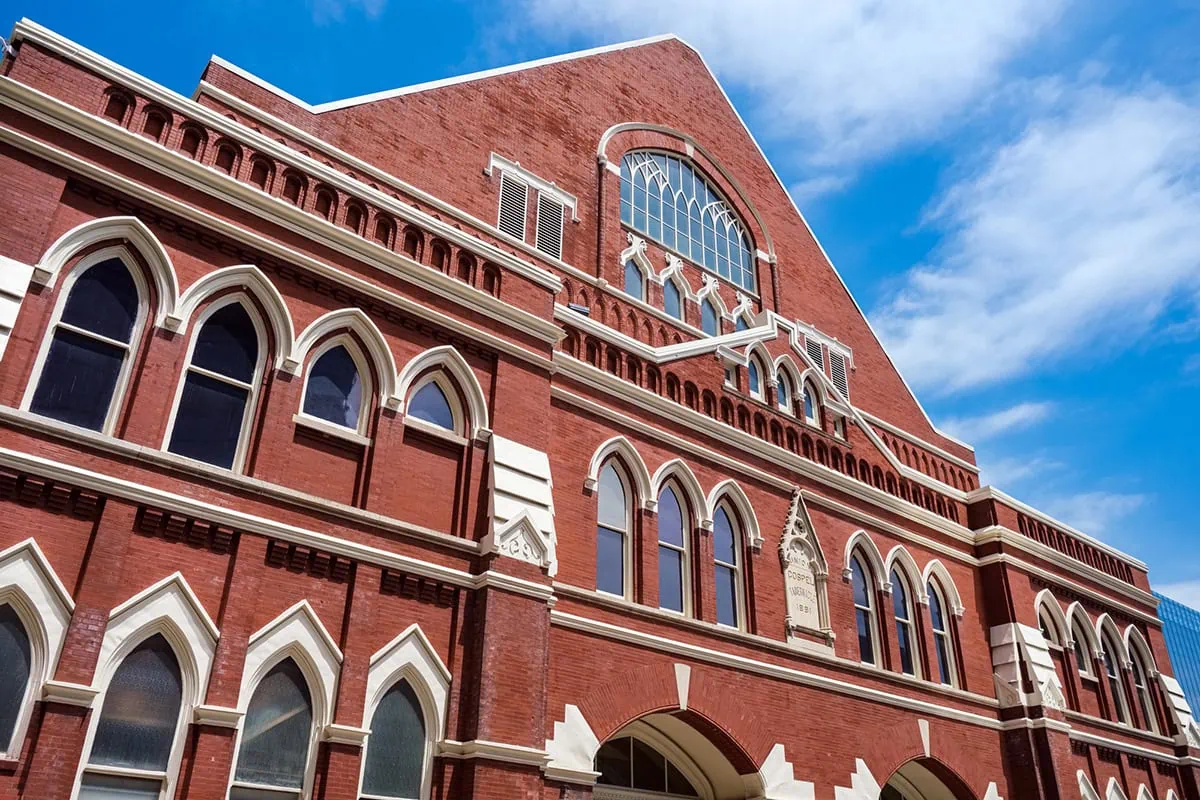
Ryman Hospitality Properties (RHP) is a specialist within the hotel REIT world. Its properties don’t house bog-standard hotels like Holiday Inn and Motel 6, but instead upscale convention center resorts—and it even owns some entertainment properties, too.
On the property side, its portfolio is composed of just a handful of resorts—but these mega-hotels, including the Gaylord Opryland, JW Marriott San Antonio Hill Country, and Gaylord Rockies, represent almost 14,000 rooms and 3 million square feet of total indoor and outdoor meeting space. In entertainment, the company also owns a roughly 70% controlling ownership interest in Opry Entertainment Group, whose entities include the Grand Ole Opry, Ryman Auditorium, and WSM 650 AM; and a majority interest in festival and events business Southern Entertainment.
“RHP turned in strong 3Q26 operating results ahead of our forecasts and raised its full year outlook; relative to our estimates, the increased guide primarily reflects the better quarter,” Citi’s Nick Joseph, who rates the stock at Buy said following the company’s third-quarter report. “Despite its premium valuation to the peer group, we believe shares remain attractive and well-positioned for 2027.”
Related: 7 Best Fidelity Dividend Funds [Passive Income Picks]
Ryman is adding to its portfolio, too. The company in August announced it would buy the 409-acre Grande Lakes Orlando, which includes a 1,010-room JW Marriott and a 582-room Ritz Carlton, which is also managed by Marriott International (MAR).
“RHP’s recent acquisitions include the JW Marriott Hill Country (San Antonio) and the JW Marriott Phoenix Desert Ridge; the acquisition of Grande Lakes is in line with RHP’s recent focus on adding higher-end options to its core-group focus,” Joseph adds. “We view the move as a positive for the portfolio given operational synergies in the Orlando market and potential ADR uplift opportunities.”
As far as the dividend goes: The company had strung together several years’ worth of consecutive dividend increases up until COVID, when the company suspended its 95¢-per-share quarterly payout. That dividend returned in 2022 at a much-reduced 10¢ per share, but quickly ramped up and surpassed its pre-pandemic level. At current levels, the dividend yields well more than 3%.
If you prefer to have some exposure to hospitality, the unique nature of both its hotel properties and highly in-demand Nashville entertainment presence make Ryman one of the best REITs to buy.
Related: 12 Best Vanguard ETFs You Can Buy [Build a Low-Cost Portfolio]
4. American Tower
- REIT industry: Telecommunications
- Market capitalization: $89.8 billion
- Dividend yield: 3.8%
American Tower (AMT) is one of the largest global REITs of any flavor, and its speciality is owning and operating multitenant communications real estate. This includes telecom towers that it rents to wireless providers, fiber optic networks, data centers, and other important infrastructure components that power our digital lives.
With a portfolio of more than 148,000 properties and massive demand for telecommunications from both businesses and consumers alike regardless of the macroeconomic picture, AMT offers incredible reliability.
Related: The 11 Best Fidelity Funds to Buy Now
“The company is a leader in tower services, and while domestic mobile spending has flattened, the company is focusing on international expansion of 5G networks and growth in mobile data consumption,” Argus Research’s Ferguson says. “AMT’s strength is in its tower business model. The company owns and leases land and tower access to wireless, radio, and television companies, with multiple tenants per tower. Customers sign long-term leases (with the average lease-term extension around 20 years) and bear the costs of the transmission equipment housed on the company’s towers.”
Truist Managing Director Matthew Niknam (Buy) adds that he likes the company’s “enhanced portfolio mix, with over 70% of property NOI coming from developed markets” and “pristine balance sheet.”
American Tower might raise a few eyeballs from a dividend perspective. That’s because in the first quarter of 2024, it announced a roughly 5% cut in its payout after years of uninterrupted quarterly hikes. However, it still ended up paying out more across 2024 than it did in 2025, and it raised its payout back to $1.70 per share to kick off 2025, then again to $1.79 per share in 2026. So while AMT might not be as frequent a raiser as it once was, the dividend still is growing and continues to look secure.
Related: 10 Best ‘Rebound’ Stocks to Buy for the Rest of 2026
3. Essential Properties Realty Trust
- REIT industry: Retail
- Market capitalization: $6.1 billion
- Dividend yield: 4.7%
Essential Properties Realty Trust (EPRT) is a retail REIT, which doesn’t exactly have the best of connotations. More recently, that’s because of the hammering the sector took during COVID, but longer-term, it’s because of the hits that malls and other retail properties have suffered amid the emergence and growth of e-commerce.
Fortunately, EPRT isn’t that kind of retail REIT.
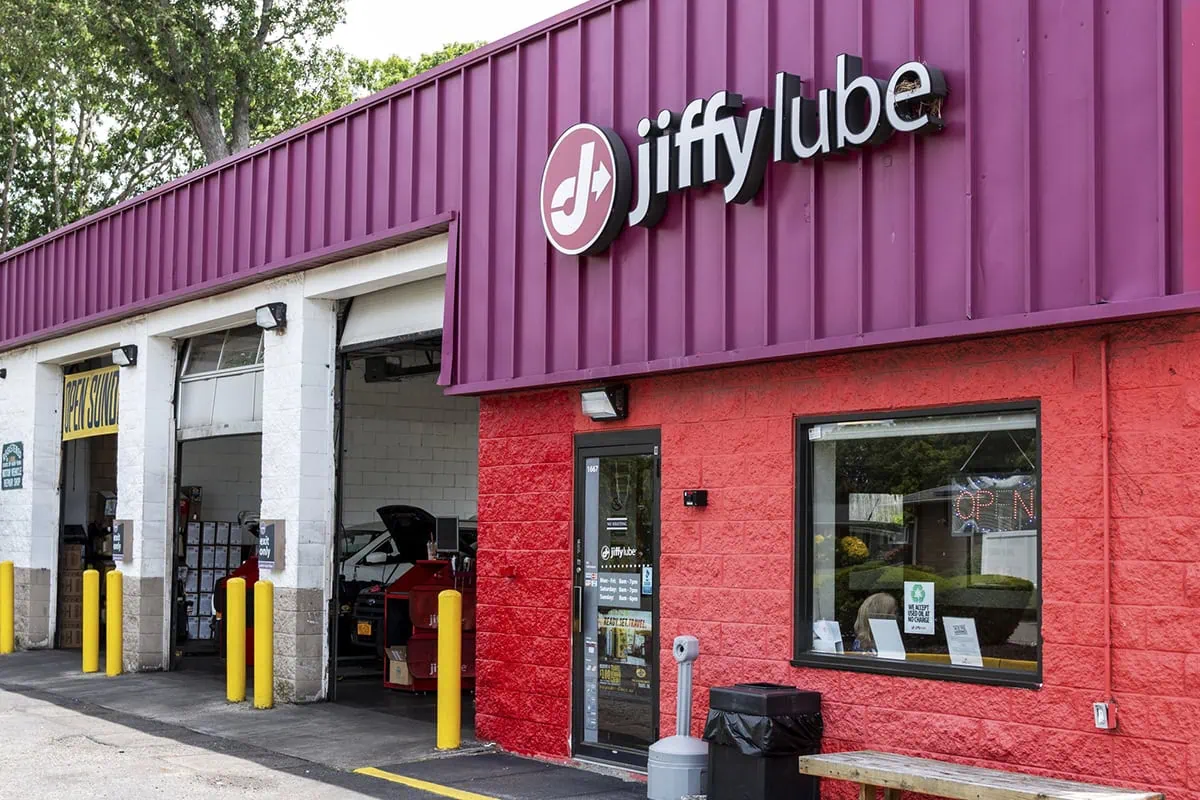
Essential Properties owns and manages 2,580 single-tenant properties spanning hundreds of tenants across 49 states. Currently, 77% of the portfolio’s cash annualized base rent (ABR) is service-based, and 15% is experience-focused. In fact, despite being a “retail” REIT, less than 3% of ABR comes from true retail—and the lion’s share of that is from grocery stores, which have been extremely durable. The remaining sliver of ABR comes from industrial properties. Top tenant groups right now include car washes, medical and dental practices, early childhood education firms, quick-service shops, and automotive service providers.
So, sure, the word “essential” might be doing a lot of work, but EPRT still isn’t as exposed to economic whims as, say, a mall where most of its stores are selling jeans or jewelry. The diversification helps.
Related: 15 Dividend Kings for Royally Resilient Income
“The top 10 tenants represent <20% of ABR (below peers), the portfolio includes 350+ total tenants, and no tenant is >3% ABR,” says Truist Managing Director Michael Lewis, who counts EPRT among the firm’s highest-conviction Buys. He adds that Essential Properties boasts a “strong balance sheet with sufficient liquidity that can support the growth strategy for the next 12 months.”
But this isn’t just a safety play; Essential Properties can deliver growth, too.
“Essential Properties Realty Trust is one of the fastest-growing net-lease REITs due to its low base and cost of capital spread,” say Stifel analysts, who also call the REIT a Buy. “This has resulted in some of the best earnings growth and among the lowest dividend payout ratios in the space.”
Essential Properties has been more than eager to share the benefits with its stock holders. The company has been raising its dividend semiannually for years; including a modest 3% hike announced in December 2025, the quarterly payout is about 30% higher than where it was five years ago.
Related: The 13 Best Mutual Funds for the Rest of 2026
2. Rithm Capital
- REIT industry: Mortgage
- Market capitalization: $5.3 billion
- Dividend yield: 10.9%
Most REITs that you read about tend to be “equity REITs,” which deal in physical real estate. Specifically, they own (and sometimes operate or manage) properties, whether that’s apartments, office buildings, hotels, warehouses, you name it.
But “mortgage REITs” deal in paper real estate. That typically takes the form of residential and/or commercial mortgages, as well as mortgage-backed securities (MBSes). An mREIT will borrow money at short-term interest rates. It will take that money and buy mortgages, MBSes, and/or other mortgage-related securities. It will then earn income from the interest generated by these products—and use much of this profit to pay dividends to its shareholders. In fact, mREITs tend to have higher dividend yields than their traditional real estate cousins.
Rithm Capital (RITM) is technically a mortgage REIT, though it looks much different than the other mREITs that appear later in this list. This “hybrid” mREIT has numerous businesses, including alternative asset management. RITM invests in residential mortgages loans, consumer loans, single-family rentals, mortgage servicing rights (MSRs), residential transitional loans, secured lending and structured products, and commercial real estate.
Ever since the 2020 financing crisis, the company has transformed its business model, growing its mortgage servicing business while also acquiring a variety of debt-related investment opportunities. It continues to be acquisitive, too, completing deals to acquire an alternative asset manager (Crestline Management) and an owner-operator of Class A properties (Paramount Group) in December 2025.
Related: Best Fidelity Retirement Funds for a 401(k) Plan
“The stock has been down lately due to growing concerns in the private-credit sector. However, we believe that the market is lumping alternative managers together and ignoring RITM’s other business lines,” writes Argus Research analyst Kevin Heal (Buy). “It continues to grow its mortgage-servicing business, refine its mortgage-recapture process with recent partnerships, and take advantage of new debt-related investment opportunities.” Indeed, net servicing revenues helped push RITM to a stronger-than-expected third-quarter report.
The pros love the new-look Rithm Capital; every one of the 11 analysts covering the stock call it a Buy. “We believe RITM remains a best-in-class REIT that has diversified its revenue streams and has consistently delivered strong earnings comfortably above its dividend,” add Keefe, Bruyette & Woods analysts, who rate the stock at Outperform.
As for the dividend: While it has remained stagnant for years, it still translates into a double-digit yield at current prices.
Featured Financial Products
1. Millrose Properties
- REIT industry: Residential real estate sites
- Market capitalization: $4.3 billion
- Dividend yield: 12.2%
Millrose Properties (MRP) isn’t a run-of-the-mill residential REIT. In fact, it’s a trailblazer.
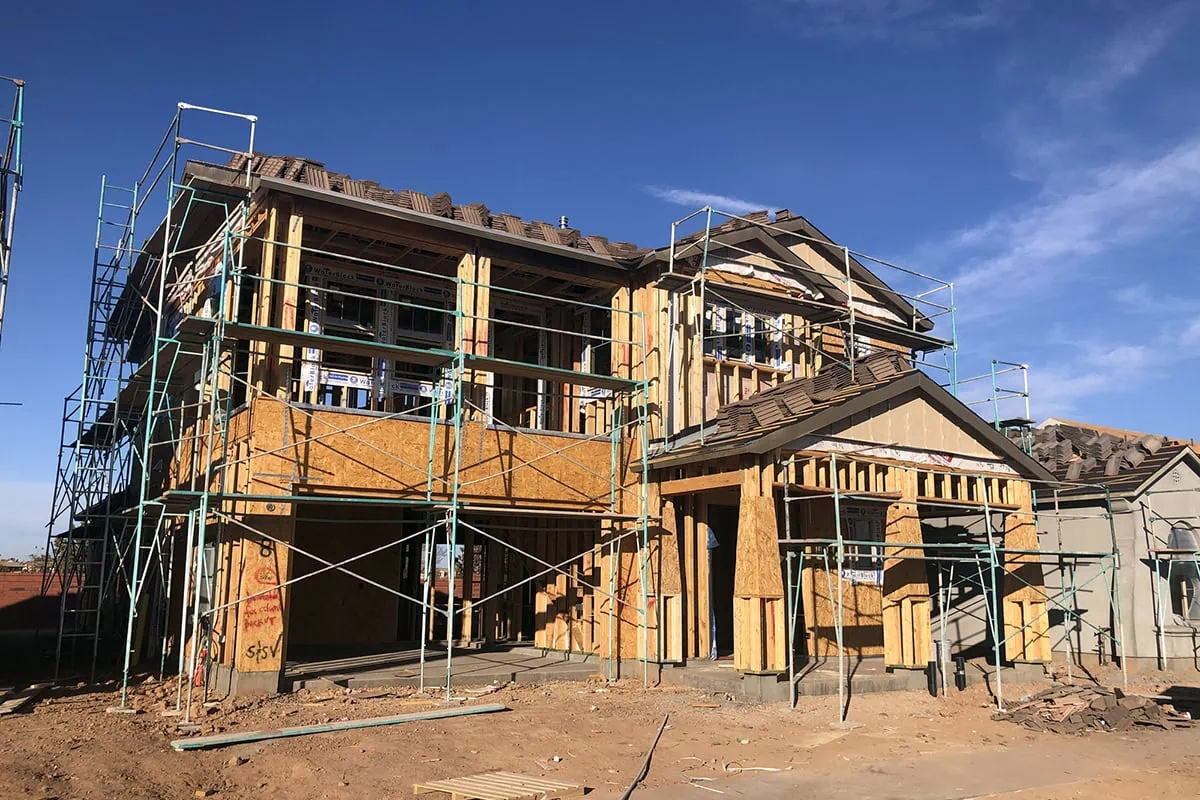
Millrose was a part of homebuilder Lennar (LEN) until it was spun off in 2024. It buys and develops residential land, then turns around and sells its finished homesites back to Lennar and other homebuilders via options contracts at set fees.
Related: 8 Low- and Minimum-Volatility ETFs for Peace of Mind
Because of its relative newness and novelty, MRP doesn’t exactly have a crowded coverage base. But most of the few Wall Street analysts assigned to the company like what they see: the stock garners five Buys, one Hold, and no Sells. The bull camp includes Citi’s Nick Joseph, who rates the stock at Buy and is warming on the company’s landbanking partnership with real estate development company JPI.
“In speaking with large apartment developers, institutional capital focused on multifamily landbanking is scarcer than we assumed, and developer equity costs are likely higher than MRP’s option yield—creating an opportunity for MRP to selectively offer permanent financing between traditional debt and equity,” he says.
Joseph is less impressed with Millrose’s investment in single-family rentals, which the company has now paused.
Related: 11 Best Vanguard Funds for the Everyday Investor
“We believe the investment in the SFR-program will remain ‘immaterial,’ if for no other reason than MRP is near its leverage limits, but we believe the more pressing question is whether MRP can regain shareholder trust,” he says. “The $250 million buyback is a move in the right direction and we anticipate there could be others. Ultimately, we remain Buy-rated because we believe it’s in MRP and LEN’s interest for MRP to find success, as we calculate over $1bn in value to LEN versus other landbanking alternatives at higher-rates/deposit amounts and less flexible terms. Also, we like the underlying core-business and discounted valuation, which already embeds significant risk and value destruction.”
Perhaps most noteworthy is an extremely aggressive dividend. The company kicked off its program in April 2025 with a prorated 38¢ quarterly distribution, which became 69¢ in July. That dividend has continued to grow in every quarter since; the most recent 79¢ payout comes out to a 12%-plus yield at current prices
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, our free retirement planning newsletter.
Can You Buy REITs in Funds?
Buying individual REITs like the ones above can be an effective way to tap into the real estate market using publicly traded stocks. But there are also REIT mutual funds and exchange-traded funds (ETFs) out there that provide diversified ways to invest across the sector in one simple holding.
For instance, the Vanguard Real Estate ETF (VNQ) has $38 billion in total assets under management (and that doesn’t include assets under the mutual fund shares). It’s invested in 140 top REITs right now, and it yields a very healthy 3.6%.
REIT ETFs carry their own unique risks, but they can be another effective way to gain exposure to real estate investments in your portfolio and provide consistent retirement income.
Related: The 16 Best ETFs to Buy for the Rest of 2026
Want to talk more about your financial goals or concerns? Our services include comprehensive financial planning, investment management, estate planning, taxes, and more! Schedule a call with Riley to discuss what you need, and what we can do for you.
How Else Can You Buy Real Estate?
Typically, if you want to own stock in a real estate company, you have to invest through the public markets. But equity crowdfunding makes it possible for everyday investors to secure a stake in privately held real estate businesses.
Equity crowdfunding platforms typically allow for small investments (read just hundreds or even tens of dollars) in a wide range of businesses. The platform is usually paid through either a monthly fee or by collecting a percentage of the funds raised for the business. And generally speaking, these platforms provide high ease of use compared to many other types of real estate investments.
Related: 7 Best Real Estate Crowdfunding Sites + Platforms
Our Equity Crowdfunding Pick: EquityMultiple
Some real estate crowdfunding platforms only allow you to invest in property portfolios. However, some platforms, such as EquityMultiple, also allow you to invest in individual properties—in this case, commercial real estate (CRE).
EquityMultiple carries a minimum $5,000 initial investment and is limited to accredited investors. However, those investors have access to individual commercial real estate deals, funds, and even diversified short-term notes.
For those interested in learning more about EquityMultiple, consider signing up for an account and going through their qualification process.
Related: The 10 Best Dividend Stocks for Beginners in 2026
Related: The 10 Best Dividend ETFs to Buy Now
We love exchange-traded funds (ETFs) because they can provide one-click access to hundreds, even thousands of stocks, while charging often minuscule fees.
One way to put that low-cost diversification to work? Collecting dividends. But trying to choose from literally hundreds of income-producing funds could take up a lot more time than you have. So let us help you narrow the field—check out our list of 10 top dividend ETFs.
Related: 10 Dividend Stocks That Pay Us Each and Every Month
The vast majority of American dividend stocks pay regular, reliable payouts—and they do so at a more frequent clip (quarterly) than dividend stocks in most other countries (typically every six months or year).
Still, if you’ve ever thought to yourself, “it’d sure be nice to collect these dividends more often,” you don’t have to look far. While they’re not terribly common, American exchanges boast dozens of monthly dividend stocks.
Please Heart ❤️, Follow and Subscribe
Did you find this article helpful?
- Click the Heart Button.
- Follow WealthUpdate —-> https://flipboard.com/@WealthUpdate
- Subscribe to Retire With Riley, our free weekly retirement planning newsletter.